Theta Gainers Delta Neutral Intraday Algo Strategy: સંપૂર્ણ build
આ લેખ અંગ્રેજીમાંથી અનુવાદિત છે. મૂળ લેખ અંગ્રેજીમાં વાંચો
Theta Gainers delta-neutral intraday strategy દરરોજ 9:22 એ એક out-of-the-money call અને put વેચે છે, પછી આખો દિવસ position ને સંતુલિત રાખે છે: જ્યારે પણ એક leg નું premium 30% વધે, એ બીજો leg બંધ કરે છે અને એને વધતા leg જેટલી કિંમતના strike પર ફરી વેચે છે. Legs પર કોઈ fixed target કે stop નથી; risk નું કામ adjustments અને universal exit કરે છે.
Strategy પાછળનો વિચાર
Theta Gainers YouTube channel એ આને intraday option-selling strategy તરીકે બતાવી હતી. Call અને put વેચવાથી premium મળે છે જે દિવસ દરમિયાન ઘટતું જાય છે. જોખમ એકતરફી ચાલનું છે: એક leg નું premium ફૂલી જાય છે જ્યારે બીજાનું ઘટે છે, અને position neutral રહેતી નથી.
Fixed stop loss ને બદલે, strategy ફરી સંતુલન કરે છે. જે leg કામ કરે છે એનો નફો લે છે અને એને market ની નજીક ફરી વેચે છે, જેથી બંને legs માં ફરી સરખાં premiums હોય. સરખાં premiums નો અર્થ મોટે ભાગે ઉલટી દિશાના સરખા deltas થાય છે, અને અહીં "delta neutral" નો અર્થ એ જ છે: કોઈ પણ દિશામાં નાની ચાલથી position પર લગભગ અસર થતી નથી.
નિયમો
એક adjustment, step by step
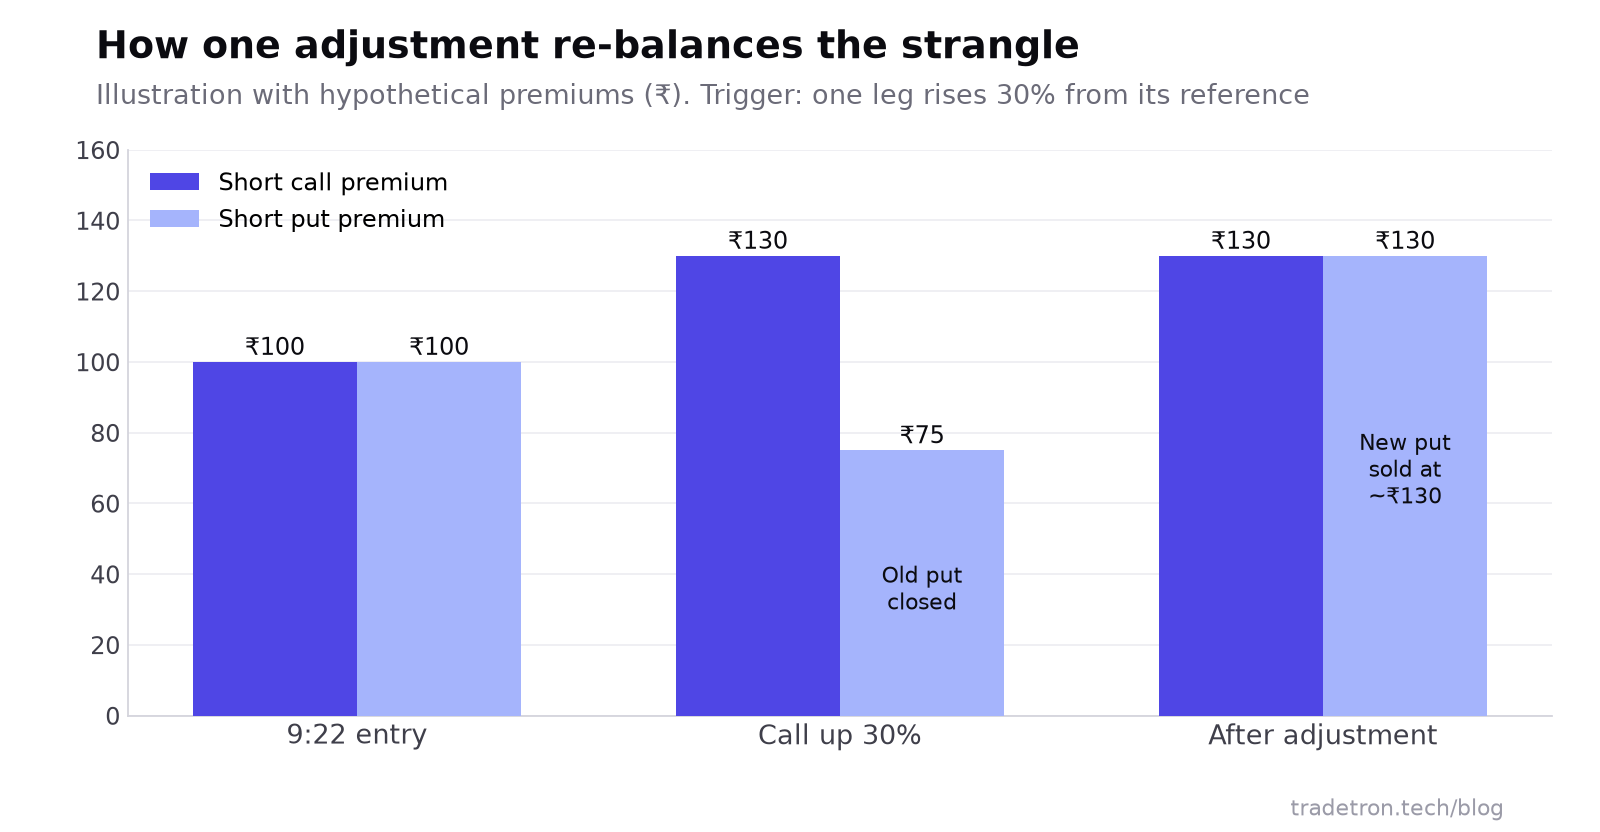 કાલ્પનિક premiums સાથે એક adjustment cycle
જો તેજી ચાલુ રહે, તો એ જ ફરી થાય છે, દર વખતે નફાવાળી બાજુ book કરીને એને નજીક લાવવામાં આવે છે. જો market પલટાય, તો નવો put વધતો leg બને છે અને call roll થાય છે.
Tradetron પર build કેવી રીતે કામ કરે છે
આ strategy Tradetron ના ત્રણ building blocks એક સાથે કામ કરતા હોવાનું સારું ઉદાહરણ છે.
1. સ્વચ્છ entry
Entry condition માં AND થી જોડેલા બે checks છે: Time ≥ 922, અને Positions Detail માં open quantity શૂન્ય, જેથી strategy બે વાર entry ન લઈ શકે.
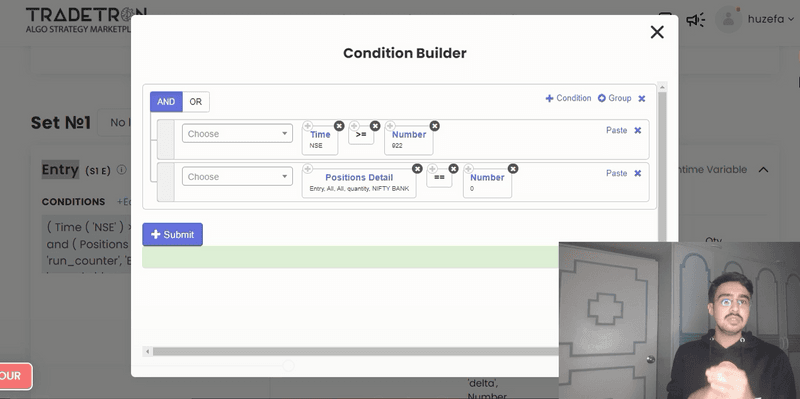 Entry condition: સમય 9:22 કે પછીનો છે અને કોઈ open position નથી
2. Memory તરીકે runtime variables
"Call 30% ઉપર છે" જેવા adjustment નિયમ માટે call નો reference price જાણવો પડે, અને પહેલા roll પછી હવે call કયું instrument છે એ પણ. Runtime variables આ સાચવે છે:
| Variable | શું રાખે છે | ક્યાંથી ભરાય છે |
|---|---|---|
| ce_ins / pe_ins | Call / put નું instrument name | Traded Instrument Name |
| ce_strike / pe_strike | એમના strikes | Traded Instrument (Field: strike) |
| ce_price / pe_price | એમના reference prices | Traded Instrument (Field: price) |
દર વખતે leg બદલાય ત્યારે variables update થાય છે, જેથી આગલો 30% check નવા leg ના price થી મપાય.
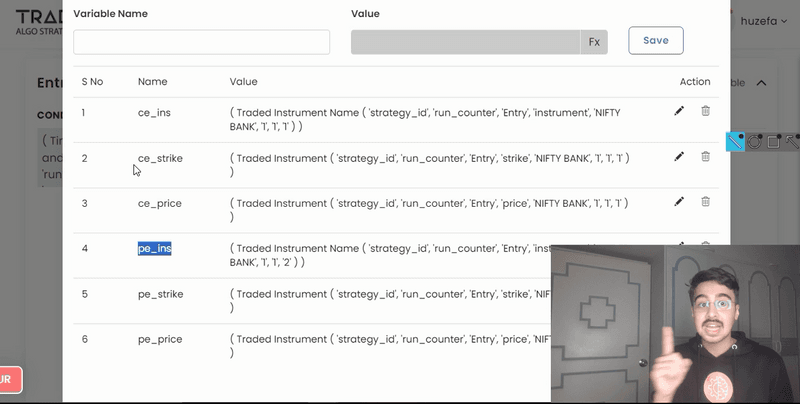 દરેક leg પર નજર રાખતા runtime variables
3. Legs roll કરતાં repairs
Adjustments Repair conditions છે: "LTP of ce_ins ≥ ce_price × 1.3" put બાજુનો roll ચલાવે છે, અને એની સામેની condition call બાજુનો roll ચલાવે છે. Repair ની positions નફાવાળો leg square off કરે છે અને premium થી પસંદ કરેલા strike પર, વધતા leg ના હાલના price ની નજીક, નવો leg ખોલે છે. Condition દિવસ દરમિયાન વારંવાર ચાલી શકે છે, એટલે એ Repair Continuous છે, Repair Once નહીં. ફરક માટે Repair Once અને Repair Continuous જુઓ.
4. Universal exit અને advanced settings
Universal Exit market બંધ થાય એ પહેલાંના નક્કી સમયે બધું બંધ કરે છે, કે strategy નો કુલ P&L તમારી loss કે profit limit પાર કરે તો એ પહેલાં. Advanced Settings માં તમે limit orders set કરી શકો છો, અને જો quantity તમારો broker કે exchange એક order માં સ્વીકારે એનાથી વધારે હોય તો મોટા orders ને નાના orders માં વહેંચી શકો છો.
આજે કયા index પર ચલાવવી
November 2024 થી, દરેક exchange પાસે ફક્ત એક weekly index expiry છે: NSE પર NIFTY 50 અને BSE પર SENSEX. BANK NIFTY, FINNIFTY અને MIDCPNIFTY options ફક્ત monthly છે. NSE ની weekly expiries મંગળવારે અને BSE ની ગુરુવારે આવે છે.
| Index | ઉપલબ્ધ expiry | આ intraday strategy માટે યોગ્યતા |
|---|---|---|
| NIFTY 50 | Weekly (મંગળવાર) અને monthly | મૂળ build ની સૌથી નજીક |
| SENSEX | Weekly (ગુરુવાર) અને monthly | BSE પર એ જ રીતે કામ કરે છે |
| BANK NIFTY | ફક્ત monthly | શક્ય છે, પણ expiry થી દૂર હોય ત્યારે intraday માં premiums ધીમે ઘટે છે |
Index બદલો ત્યારે lot sizes ફરી તપાસો (NIFTY હવે lot દીઠ 65 છે) અને 20-delta અને 30% ના numbers એ index ની સામાન્ય દૈનિક ચાલને હજી અનુકૂળ છે કે નહીં એ પણ.
ફાયદા
- કોઈ fixed stop loss નથી જે એક spike થી લાગી જાય
- Market ચાલે તેમ કામ કરતા leg નો નફો લે છે
- દિવસ દરમિયાન position ને neutral ની નજીક રાખે છે
- સંપૂર્ણ mechanical, એટલે screen જોયા વગર ચાલી શકે છે
મર્યાદાઓ
- મજબૂત trend ના દિવસોમાં વારંવાર adjustments કરવા પડી શકે છે
- દરેક roll short options ને market ની નજીક લાવે છે
- ઘણા legs એટલે વધારે brokerage, taxes અને slippage
- Strategy સ્તરની loss limit પર ઘણો આધાર રાખે છે
એ જ channel નો લાંબા સમયગાળાનો અભિગમ Theta Gainers monthly options strategy માં છે. બે legs ના sell ની મૂળભૂત બાબતો માટે short strangle vs short straddle વાંચો.
વારંવાર પૂછાતા પ્રશ્નો
Delta-neutral strategy શું છે?
Delta-neutral position એ રીતે બનાવાય છે કે underlying ની નાની ચાલથી એની value માં ભાગ્યે જ ફરક પડે: એના legs ના positive અને negative deltas લગભગ એકબીજાને રદ કરે છે. Option sellers direction પર દાવ લગાવ્યા વગર time decay થી કમાવા એનો ઉપયોગ કરે છે.
30% adjustment કેવી રીતે કામ કરે છે?
જ્યારે કોઈ પણ short option નું premium એના reference price થી 30% ઉપર જાય, ત્યારે strategy બીજો, નફાવાળો leg બંધ કરે છે અને એ બાજુ વધતા leg ના premium ની નજીકના premium વાળો નવો option વેચે છે. પછી બંને legs માં સરખાં premiums હોય છે, અને નવા prices આગલો reference બને છે.
9:15 ને બદલે 9:22 એ entry શા માટે?
ખૂલ્યા પછીની પહેલી થોડી મિનિટોમાં overnight gap અને પહોળા spreads હોય છે. થોડી મિનિટ રાહ જોવાથી option prices સ્થિર થાય છે, જેથી 20-delta strikes અને એમનાં premiums શરૂઆતની ભાગદોડને બદલે market ને દર્શાવે.
શું હું હજી આ BANK NIFTY પર ચલાવી શકું?
BANK NIFTY માં હવે ફક્ત monthly expiries છે. તમે logic monthly contract પર ચલાવી શકો છો, પણ expiry થી દૂર intraday decay ધીમો હોય છે. મૂળ weekly સ્વભાવ જાળવવા, એને NIFTY (NSE, મંગળવારની expiry) કે SENSEX (BSE, ગુરુવારની expiry) પર ચલાવો.
આ strategy stop loss વાપરે છે?
અલગ-અલગ legs પર નહીં. Risk adjustments થી અને એક universal exit થી નિયંત્રિત થાય છે જે આખી strategy ને નક્કી સમયે, કે કુલ P&L તમે પસંદ કરેલી loss limit પાર કરે ત્યારે, બંધ કરે છે.