Strangle Option Strategy: A Complete Guide (Long and Short)
A strangle is an options strategy that combines an out-of-the-money (OTM) call and an OTM put on the same underlying and expiry, at different strikes. Buy both (a long strangle) and you profit from a big move in either direction. Sell both (a short strangle) and you profit if the price stays between the strikes, in exchange for open-ended risk.
How a strangle works
With NIFTY at 25,000, a strangle uses one call above the market and one put below it, for example the 25,300 call and the 24,700 put. Neither option has intrinsic value when you enter: both premiums are pure time value.
- If you buy them, you need NIFTY to move far enough beyond one strike to recover the cost of both options.
- If you sell them, you keep both premiums if NIFTY stays between the strikes until expiry.
- ₹110 25,300 call premium (example)
- ₹105 24,700 put premium (example)
- ₹215 total premium per unit
- ₹13,975 total per lot of 65
Strangle payoff: long vs short
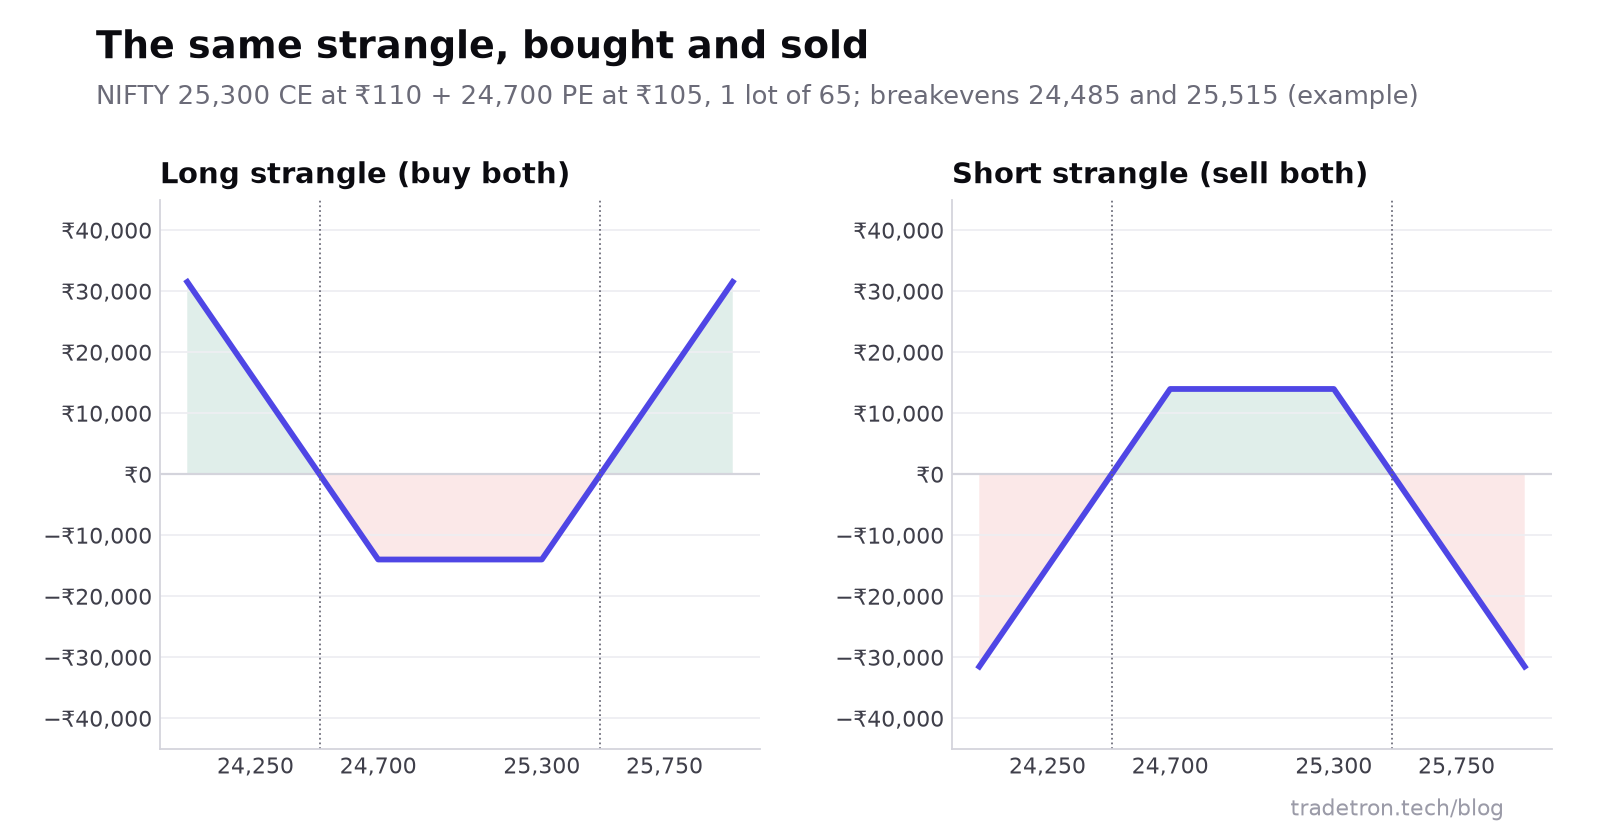 A long and a short strangle on the same strikes are mirror images
| Long strangle | Short strangle | |
|---|---|---|
| Position | Buy OTM call + buy OTM put | Sell OTM call + sell OTM put |
| Market view | Big move, direction unknown | Range-bound, quiet market |
| Volatility view | IV likely to rise | IV high, likely to fall |
| Maximum profit | Unlimited above; large below | Total premium (₹13,975 per lot in the example) |
| Maximum loss | Total premium (₹13,975 per lot) | Unlimited above; large below |
| Upper breakeven | 25,300 + 215 = 25,515 | 25,515 |
| Lower breakeven | 24,700 − 215 = 24,485 | 24,485 |
| Time decay | Works against you | Works for you |
The long strangle: trading a big move
A long strangle suits situations where you expect a sharp move but don't know which way:
- Scheduled events: company results (for stock options), the Union Budget, RBI policy decisions, election results.
- Tight ranges: after a long period of compression, such as a Bollinger Band squeeze, a breakout often follows.
- Low implied volatility: cheap premiums lower the bar for breaking even, and a rise in IV adds value to both legs.
How long strangle traders manage risk:
- Exit on a time stop. Time decay speeds up near expiry; many buyers exit if the move hasn't come within a set number of days.
- Take profit on one leg. After a big move, the winning leg carries the trade. Some traders close it and leave the cheap losing leg as a free option on a reversal.
- Buy more time. A longer expiry costs more but decays more slowly.
The short strangle: getting paid for a quiet market
The short strangle is one of the most widely traded option-selling setups on NIFTY. Sellers like it because the profit zone is wide and time decay works for them every day.
The risk is a sharp, sustained move. In the example, at 26,000 the short strangle loses (700 − 215) × 65 = ₹31,525 per lot, more than twice the maximum profit, and the loss keeps growing beyond that.
How short strangle traders manage risk:
- Per-leg stop-loss. Exit a leg if its premium rises by a set percentage above the selling price, for example 30–50%.
- Combined loss limit. Exit both legs if the strategy's loss reaches a fixed rupee amount.
- Adjust the untested leg. When the market moves towards one strike, roll the other leg closer to collect more premium. This narrows the range, so use it with a hard loss limit.
- Buy wings. Buying further OTM options turns the short strangle into an iron condor with a capped loss and lower margin.
- Avoid events and overnight gaps unless the position is hedged.
How to choose strikes for a strangle
There are three common ways to choose strangle strikes:
| Method | Example | Why traders use it |
|---|---|---|
| Fixed distance | 300 points either side of spot | Simple and consistent |
| By premium | The call and put trading closest to ₹100 | Keeps the credit (or cost) similar from day to day |
| By delta | Call and put with delta near 0.20 | Adjusts for volatility automatically |
Strikes further out give a short strangle more room, but collect less premium. For a long strangle, further strikes are cheaper but need a bigger move. Equal distances keep the position direction-neutral; moving one strike closer adds a mild directional tilt.
Strangle vs straddle
A straddle uses the same at-the-money strike for both options. Compared with it, a long strangle is cheaper but needs a bigger move; a short strangle collects less but has a wider profit zone. Read the full side-by-side in straddle vs strangle, or see the short straddle guide and the long straddle guide.
Frequently asked questions
What is a strangle option strategy?
A strangle combines an out-of-the-money call and an out-of-the-money put on the same underlying and expiry. Buying both bets on a large move in either direction; selling both bets that the price stays between the two strikes.
What is the difference between a strangle and a straddle?
A straddle uses one at-the-money strike for both the call and the put. A strangle uses two different out-of-the-money strikes, which makes it cheaper to buy and gives sellers a wider profit range, but it collects less premium.
How do you calculate strangle breakevens?
Add the total premium (call + put) to the call strike for the upper breakeven, and subtract it from the put strike for the lower breakeven. With a 25,300 call and 24,700 put costing ₹215 together, the breakevens are 25,515 and 24,485.
Is a short strangle risky?
Yes. Its maximum profit is the premium received, but losses are unlimited on the upside and very large on the downside if the market moves sharply. Stop-losses, position sizing and buying protective wings are how traders manage it.
When should you buy a strangle?
When you expect a large move but are unsure of its direction, and when implied volatility is relatively low so premiums are cheap. Buying right before a well-known event is often expensive because IV has already risen.
Can a strangle be automated?
Yes. On Tradetron you can set the entry time, strike rules, stop-losses, targets and exits once, backtest them, and run the strategy Live Offline or through your broker.