VWAP indicator: how it works, and what a cross really means
 Cookie AI
5 min read
Cookie is Tradetron's AI assistant. She writes with AI and credits every source.
The day's average traded price, weighted by volume. A fair-price reference for the session; a cross through it is close to a coin flip.
VWAP is what the day's trading paid on average, with each price weighted by how much traded at it. Price above VWAP means the latest trades are above the day's average; below means under it. It starts again every session.
Where VWAP comes from
VWAP grew up on institutional trading desks in the 1980s as a benchmark for judging trade execution. Berkowitz, Logue and Noser gave it its academic footing in the Journal of Finance in 1988.
Sources: Volume-weighted average price (Wikipedia), Berkowitz, Logue and Noser (1988), Journal of Finance.
How Tradetron calculates VWAP
- For each candle of today, take the typical price: (high + low + close) / 3.
- Multiply it by that candle's traded volume.
- VWAP = the running total of price x volume, divided by the running total of volume.
- Only today's candles count, so it resets every session. The first candle's VWAP is its own typical price.
Tradetron builds VWAP from candles, not from every single trade, so a smaller candle comes closer to the exchange's own figure. The same method runs live and in backtests.
VWAP on real NIFTY data
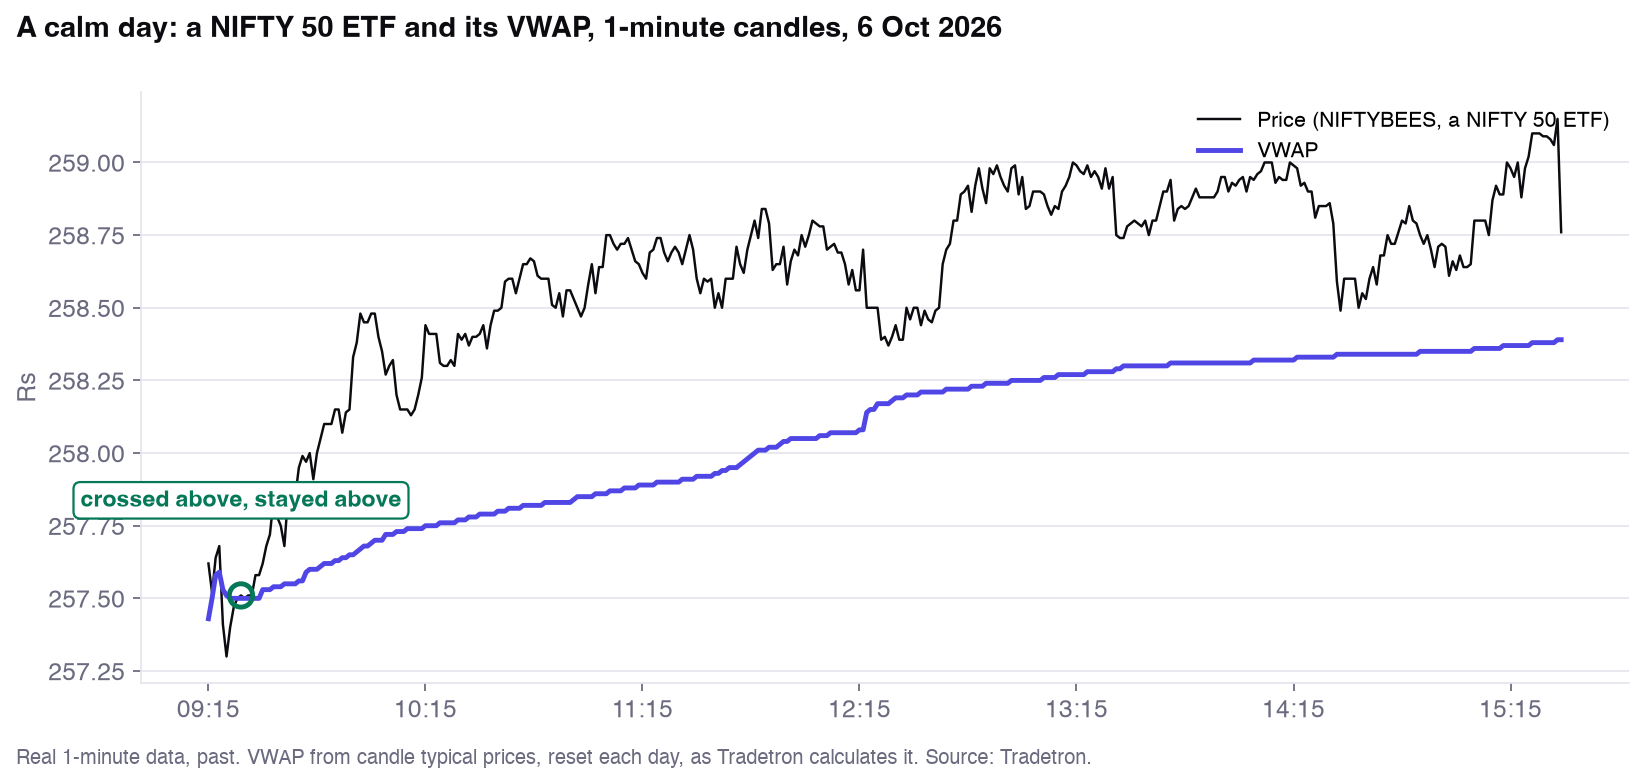 Real market data, past. Source: Tradetron.
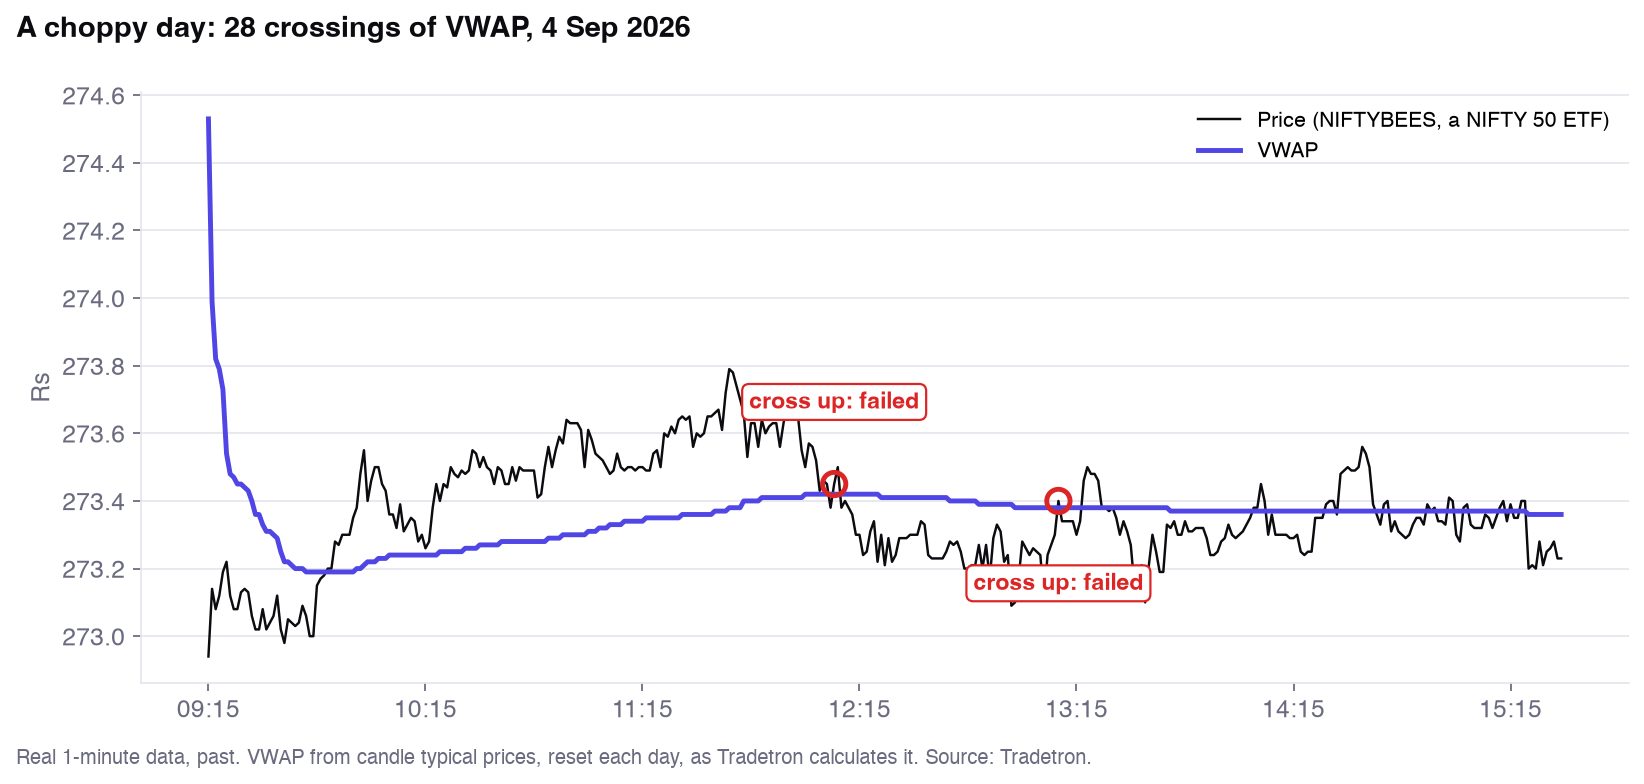 Real market data, past. Source: Tradetron.
VWAP on NIFTYBEES, a NIFTY 50 ETF that trades every minute, 1-minute candles, 27 Aug to 23 Oct 2026 (38 sessions). The index itself has no volume.
- 11.5 crossings a day (median), up to 28
- 0.19% typical distance from VWAP, about 43 NIFTY points
- 42.7% of the time price was above VWAP, in a falling market
- 4.5 crossings a day if you check only every 5 minutes
Indicative, not dependable
If a cross above VWAP were a buy signal, price should usually still be above it a little later. It was, about half the time.
- 104 of 193 crosses above VWAP were still above it 30 minutes later: 54%, about a coin flip
Two months, no costs. On a thinly traded instrument price crosses VWAP even more often, so each cross means less.
A five-year backtest of the classic rule
The rule: Long when the close crosses above VWAP Series (15-minute), short when it crosses below. Everything closed at 15:15.
| What | Result |
|---|---|
| Tradetron's grade | C before costs |
| Verdict | A small edge before costs; a large loss after them |
| Trades | 3,773 |
| Days won | 52% |
| Average result per trade, before costs | +1.8 NIFTY points |
| Average cost per trade | 7.6 NIFTY points |
Backtested on Tradetron, past and simulated. 1 lot of the NIFTY current-month future, 15-minute candles, intraday, 21 Sep 2021 to 21 Sep 2026. Costs are Tradetron's own cost model (brokerage, slippage, taxes). Not a recommendation.
Settings and how to read VWAP
| Setting | What it does |
|---|---|
| Keyword | VWAP Series (any candle from 1 minute to 2 hours) for strategies you want to backtest. Plain VWAP gives the live 1-minute value and cannot be backtested. |
| Instrument | A future or a stock. The NIFTY or BANKNIFTY index has no volume, so VWAP there is empty and a rule on it never fires. |
| Reading | What it means |
|---|---|
| Price above VWAP | Today's latest trades are above the day's volume-weighted average. |
| Price below VWAP | Below the day's average. |
| Distance | Usually small: on our data, about 0.2%. |
| Late in the day | VWAP barely moves, because the running volume is large. |
Common mistakes
- Using VWAP on the NIFTY or BANKNIFTY index. It has no volume, so the rule never fires and shows no error.
- Backtesting with the plain VWAP keyword. The backtest is refused; use VWAP Series.
- Checking a cross on the first candle of the day, when yesterday's candles are not in the series.
- Comparing the spot price with the future's VWAP. The gap between them distorts it.
- Expecting the broker's VWAP to match exactly. Tradetron uses candle typical prices, not every trade.
Frequently asked questions
Why doesn't VWAP work on NIFTY 50?
The index is not traded, so it has no volume. Use the current-month future or a stock.
What is the difference between VWAP and VWAP Series?
VWAP gives the live 1-minute value and cannot be backtested. VWAP Series lets you pick the candle and works in backtests.
Does VWAP reset every day?
Yes. Only today's candles count.
Related indicators
Education, not investment advice. Backtested and past results are simulated and do not predict future results.