Quantitative Trading: A Practical Guide for Indian Traders
Quantitative trading is trading with rules built from data: you form an idea about how prices behave, express it as precise rules, test those rules on historical data, and trade them only if the evidence holds up. It replaces gut feel with measurable logic. When the rules are also executed automatically, quant trading becomes algorithmic trading.
Quant, algo and high-frequency trading: what's the difference?
The terms overlap, which is why they get mixed up.
| Quantitative trading | Algorithmic trading | High-frequency trading (HFT) | |
|---|---|---|---|
| Defined by | Rules derived from data and statistics | Orders placed automatically by software | Very high speed and order volume |
| Question it answers | What should I trade, and when? | How do I execute it reliably? | How do I act before others? |
| Holding period | Minutes to months | Any | Fractions of a second to minutes |
| Who does it | Retail traders to large funds | Anyone with a broker API or platform | Mostly institutions with colocated servers |
A retail trader who builds a rule from backtests and runs it on an algo platform is doing quant and algo trading at once. HFT is a separate world of infrastructure, and not what most people mean.
How quantitative trading works
- Start with a hypothesis. A plain-English idea about market behaviour: "after a strong trend day, NIFTY tends to continue in the same direction the next morning" or "a stock that falls far below its 20-day average tends to bounce."
- Turn it into exact rules. Entry, exit, stop loss, position size, and which instruments and times. If two people could read the rule differently, it isn't exact yet.
- Test on historical data. Run the rules over years of data and record every trade.
- Check it on data you didn't use to build it. Keep a later period aside and test there too (out-of-sample testing). A rule that only works on the period you designed it on is suspect.
- Run it live without risk. Trade it on live prices without sending orders, to catch timing and execution differences.
- Go live small and monitor. Compare live results with the test. Edges fade; decide in advance what would make you stop.
The main families of quant strategies
| Family | The idea | Example rule |
|---|---|---|
| Trend following | Prices that are moving tend to keep moving | Buy when the 20-day average crosses above the 50-day; exit on the reverse cross |
| Mean reversion | Prices that stretch far from normal tend to come back | Buy a stock when RSI(2) drops below 10, sell when it closes above its 5-day average |
| Relative value / pairs | Two related instruments that drift apart tend to reconverge | When the price ratio of two bank stocks moves 2 standard deviations from its average, buy the cheap one and sell the expensive one |
| Volatility / options | Option prices often carry more expected movement than the market delivers | Sell an index straddle or strangle with a fixed stop loss and a time exit |
| Factor / momentum portfolios | Stocks with certain traits tend to outperform over time | Each month, hold the 10 NIFTY 50 stocks with the strongest 6-month returns |
| Breakout | Price leaving a quiet range often starts a move | Buy when price breaks the first 15 minutes' high, stop at the range low |
Each family loses money in some market conditions: trend strategies in sideways markets, mean reversion in strong trends, option selling in sudden large moves. Quant traders often combine families for that reason.
The numbers that judge a quant strategy
A backtest report gives many numbers. These matter most:
- Expectancy: the average result per trade, per rupee risked. Above zero, after costs, is the minimum.
- Maximum drawdown: the largest peak-to-trough fall in the equity curve. This is the pain you must be able to sit through.
- Win rate and payoff ratio: how often it wins, and how big wins are compared with losses. Neither means anything without the other.
- Number of trades: 20 trades prove very little; hundreds across different market conditions say more.
- Return relative to risk: for example, annual return divided by maximum drawdown, or the Sharpe ratio.
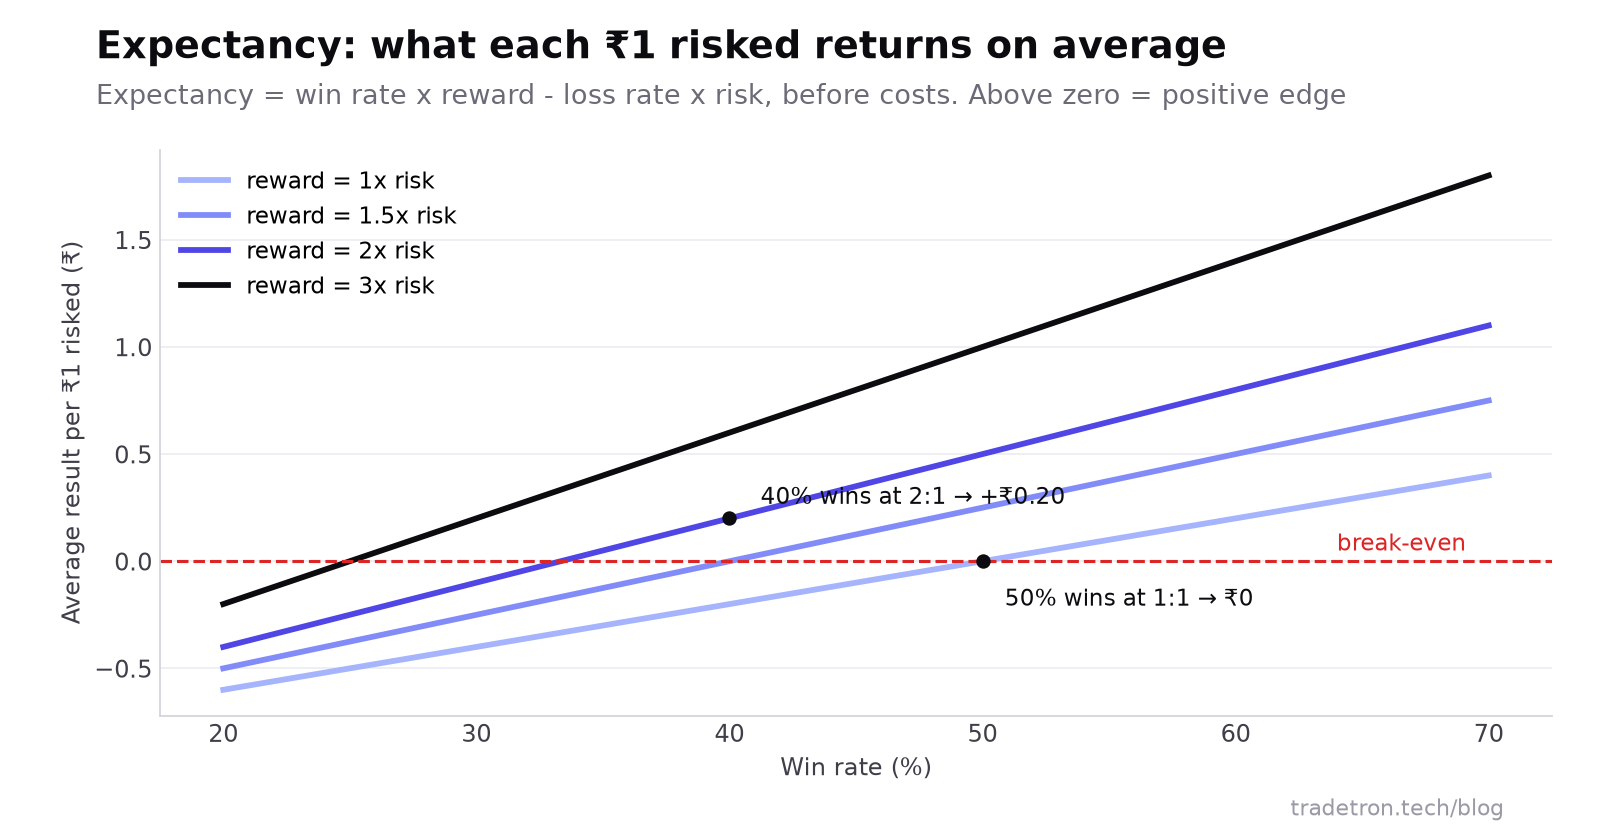 A low win rate can still be a positive edge if wins are larger than losses (before costs)
The overfitting trap
Ways to guard against it:
- Keep the rules simple and the parameters round.
- Check that nearby parameter values also work. If 20 works and 19 and 21 don't, the result is luck.
- Test out-of-sample, and across bull, bear and sideways periods.
- Include realistic costs and slippage, especially for strategies that trade often. See nine reasons your backtest doesn't match live trading.
What you need to start
Pros
- Decisions come from evidence, and you can measure whether an edge exists
- Rules are explicit, so they can be automated and reviewed
- Testing on history shows the worst periods before you live through them
- Works at any scale, from one strategy to a portfolio of them
Cons
- Past patterns can stop working as markets change
- Easy to fool yourself with overfitted backtests
- Data, testing and monitoring take real time
- Small edges can disappear after costs
Traditionally, quant trading meant writing Python, buying data, building a backtester and running servers. For rule-based strategies on Indian markets, a no-code platform covers most of that: data, backtesting, live test runs and broker execution in one place. Coding still helps for research that goes beyond what a builder's building blocks express.
Is it legal? Yes. Quant strategies follow the same rules as any algo trading in India. See is quant trading legal in India.
Keep going with how to evaluate algo strategy performance, the Sharpe ratio explained and building automated strategies without coding.
Frequently asked questions
What is quantitative trading in simple words?
It is trading based on rules built from data. You test an idea about how prices behave on historical data, and trade it only if the evidence supports it, instead of relying on opinion or gut feel.
Is quantitative trading the same as algo trading?
Not exactly. Quantitative trading is about how the rules are created (from data and testing). Algo trading is about how orders are executed (automatically by software). Most quant strategies are executed as algos, so the terms overlap.
Can retail traders do quantitative trading in India?
Yes. Retail traders can build rule-based strategies, backtest them and run them through their broker on algo platforms, within SEBI's algo trading framework. You don't need institutional infrastructure for strategies that trade at normal speeds.
Do I need to know coding or advanced maths?
Not to start. Basic statistics (averages, percentages, standard deviation) and clear rules go a long way, and no-code platforms handle the programming. Coding and deeper maths help with more advanced research.
What is a good win rate for a quant strategy?
There isn't one on its own. A 35% win rate can be profitable if winners are three times the size of losers; a 70% win rate can lose money if losers are much bigger. Look at expectancy after costs.
How do I know if my backtest is reliable?
Check it on data you didn't use to design it, across different market conditions, with realistic costs, and over enough trades. Then run it in a simulated mode on live prices before trading real money.