SEBI vs Jane Street: What the Case Means for Algo Traders
In July 2025, SEBI issued an interim order against Jane Street, the US trading firm, alleging that it manipulated the BANK NIFTY index on options expiry days to profit from much larger options positions. SEBI barred the firm from Indian markets and impounded about ₹4,843 crore. Jane Street denied wrongdoing. The case draws a sharp line between legitimate algorithmic strategies and market manipulation.
What SEBI alleged
SEBI's interim order, issued on 3 July 2025, focused on trading in the BANK NIFTY index and its constituent stocks, mainly on weekly expiry days. According to SEBI, the pattern ran like this:
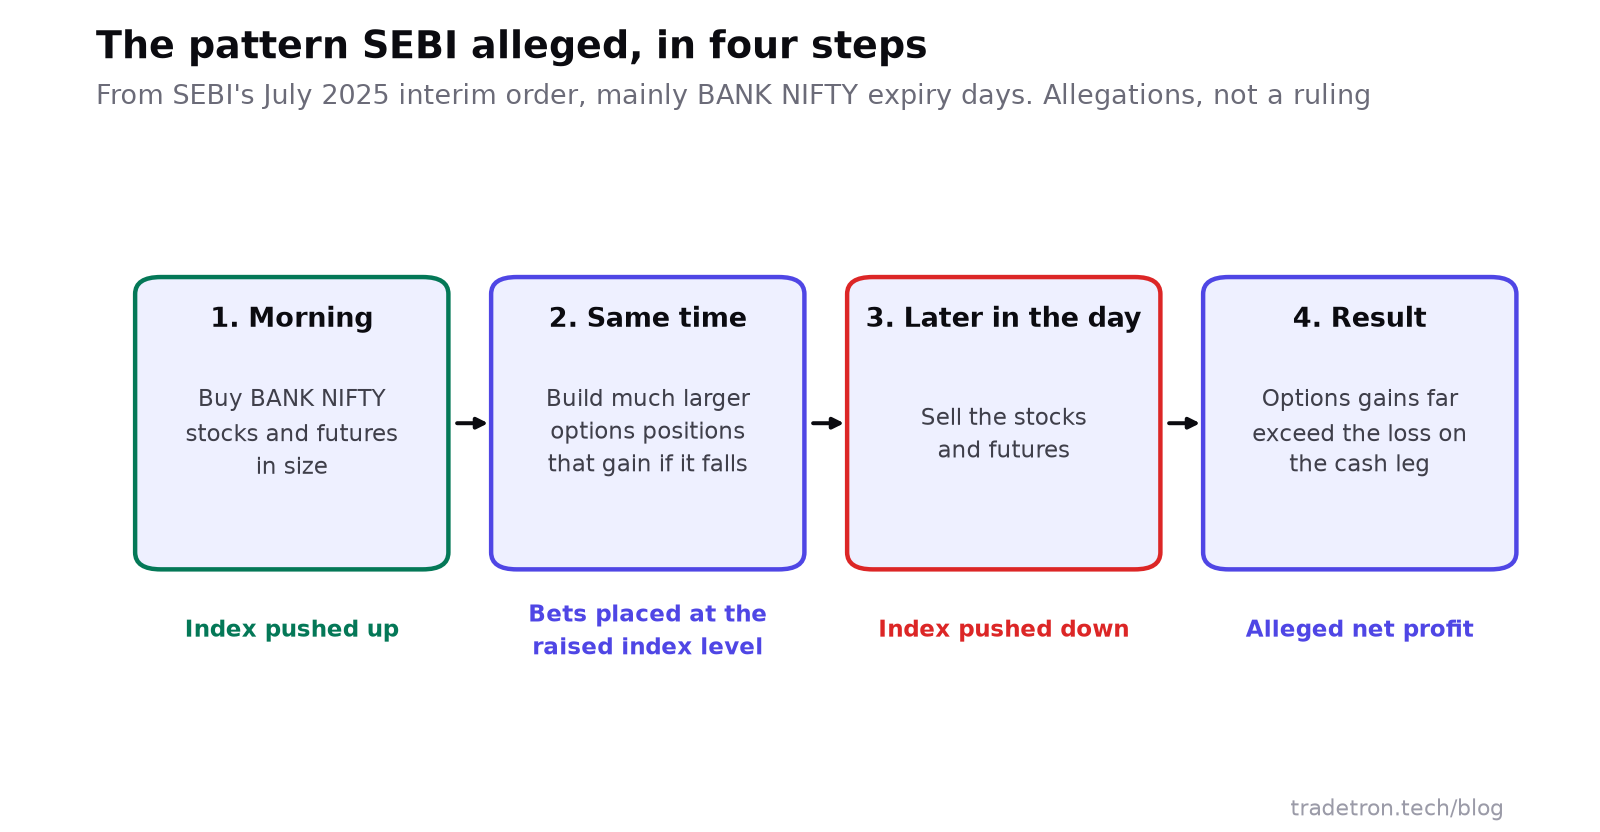 The pattern SEBI described in its interim order. These are allegations, not a final ruling
The cash and futures trades on their own lost money. SEBI's case was that they were not meant to make money: their purpose was to move the index so that much larger options positions would pay off. SEBI also alleged a second pattern near the market close, which it called "marking the close".
- ₹4,843 crore impounded by SEBI as alleged unlawful gains
- Jan 2023 – Mar 2025 the period SEBI examined
- About ₹36,500 crore profit from index options in that period, per SEBI's order
What happened next
- SEBI's order: Jane Street group entities were barred from buying, selling or dealing in Indian securities, and the ₹4,843 crore was to be deposited in an escrow account.
- The deposit: Jane Street deposited the amount, and SEBI allowed it to resume trading later in July 2025, subject to conditions against the alleged patterns.
- Jane Street's position: the firm said its trades were basic index arbitrage that kept options and stock prices in line, disputed SEBI's interpretation, and contested the order.
Because the order was interim, its findings are allegations until the proceedings conclude. Check SEBI's and the Securities Appellate Tribunal's latest orders for the current status.
Arbitrage or manipulation: where is the line?
Index arbitrage is legal and common. When an index's options or futures drift away from the price of the stocks in it, arbitrageurs buy the cheaper side and sell the dearer side, and their trades pull prices back together. That makes markets more efficient.
SEBI's argument was about intent and effect. Arbitrage reacts to price gaps; SEBI said these trades created the price moves, and that the options positions were many times larger than any hedge would need.
| Legitimate strategy | What regulators treat as manipulation |
|---|---|
| Trades react to prices the market sets | Trades are placed to move the price |
| Each leg makes sense on its own or as a hedge | One leg is meant to lose, to make another leg pay |
| Position sizes fit the hedge or the opportunity | One side is far larger than any hedge requires |
| Orders are meant to be filled | Orders are placed and cancelled to mislead (spoofing) |
| Trading pattern is the same on any day | Pattern clusters around expiry or the closing price |
Why retail traders should care
Retail traders weren't parties to the case, but they trade the same contracts. SEBI's own study of the F&O segment, published in September 2024, found that about nine in ten individual traders lost money over the three years it covered. The Jane Street order put that number next to a picture of who was on the other side of expiry-day trades.
The case also came after a run of SEBI changes aimed at expiry-day risk. Since November 2024, each exchange has only one weekly index expiry (NIFTY 50 on NSE, SENSEX on BSE), with BANK NIFTY options moving to monthly expiries. And SEBI's February 2025 framework made every retail algo order traceable through brokers.
What ethical algo trading looks like
For a retail trader building strategies, staying on the right side of the line is not hard:
- Trade to profit from price moves, not to cause them. Your strategy should work as a price taker. If it only works because of its own orders, it is a problem.
- Size orders to the market. A retail order in NIFTY futures or a liquid stock doesn't move the price. An order that is a large share of an illiquid stock's volume can.
- Only place orders you intend to fill. Placing and cancelling orders to create a false picture of demand is spoofing, whether manual or automated.
- Keep your strategy explainable. If you can describe every leg's purpose in a sentence, you are on safe ground.
- Go through a registered broker and a traceable setup. Under SEBI's rules, every algo order carries an identifier. See is algo trading legal in India.
For the rules that govern retail algos, read SEBI's algo-ID mandate. For how high-speed trading differs from retail automation, see low-latency vs high-frequency trading.
Frequently asked questions
What did SEBI accuse Jane Street of?
In its July 2025 interim order, SEBI alleged that Jane Street bought BANK NIFTY stocks and futures to push the index up, built much larger options positions that would gain if it fell, and then sold to push the index down, mainly on expiry days. SEBI also alleged manipulation near the market close.
How much money did SEBI impound from Jane Street?
About ₹4,843 crore, which SEBI treated as the unlawful gains from the alleged pattern. Jane Street deposited the amount in escrow.
Is Jane Street still banned in India?
SEBI allowed Jane Street to resume trading in July 2025 after it deposited the impounded amount, subject to conditions. The proceedings on the allegations themselves were separate; check SEBI's latest orders for the current status.
Is index arbitrage illegal in India?
No. Index arbitrage, trading the gap between an index's derivatives and its stocks, is legal and helps keep prices aligned. SEBI's case was that the trades in question created the price moves rather than reacting to them.
Does this case affect retail algo traders?
Not directly, but it shows how regulators judge any strategy, manual or automated: by its intent and its effect on prices. Retail algos that trade as price takers through a registered broker are a different world from the trading in this case.
What counts as market manipulation in algo trading?
Placing orders to move a price, spoofing (orders you don't intend to fill), wash trades with yourself, trading on unpublished price-sensitive information, and patterns designed to influence closing or settlement prices.