Before You Go Live: Why Paper Trading Can Save Your Algo Strategy

Paper trading can save your algo strategy because it is the only test that runs your exact rules on today's live market before money is at stake. A backtest tells you whether the idea worked on past data; a live simulated run tells you whether the strategy you built actually does what you meant. On Tradetron this test mode is called Live Offline: the strategy runs and records every trade, but nothing is sent to the exchange.
Backtest, Live Offline, then live: what each stage proves
Each stage answers a different question, and skipping one leaves that question for real money to answer.
| Stage | Question it answers | What it can't tell you |
|---|---|---|
| Backtest | Would these rules have worked on past data? | Whether your strategy behaves the same on live data; hindsight bias |
| Live Offline (paper trading) | Does the strategy I built do what I meant, on today's market? | Real fills, slippage, broker and margin issues |
| Small live run | Does it work with real orders and real costs? | Whether results hold at a larger size |
Five problems a live test catches that a backtest misses
1. Logic bugs in the build
A strategy is a set of conditions, and conditions interact. In a live run you see each trade as it happens, with a time stamp and a reason. Look for:
- Double entries: the entry condition stays true, and the strategy enters again on the next check.
- Missed exits: an exit condition that can never become true, so positions are only closed by the end-of-day exit.
- Stops that never arm: a stop loss tied to the wrong reference price, so it never triggers.
- Wrong instruments: a strike or expiry chosen differently from what you intended, especially around expiry days.
2. Timing
Time conditions, entry windows and exits at fixed times behave differently when the market opens with a gap, or on days with a special session. A live run shows you when your trades actually happen.
3. What happens inside a candle
Backtests usually work on bars, such as one-minute candles. A price can cross your stop and come back within the same minute, and a test that reads only each bar's open and close never sees it. Live, the stop fires. Comparing Live Offline trades with the backtest for the same days shows whether this matters for your strategy. Our article on why backtests don't match live trading covers more of these gaps.
4. Trade frequency
A rule that produced 80 trades a year in the backtest might trigger far more often on live data because of a small difference in how a condition is evaluated. Over-trading in sideways markets is a common surprise.
5. Your own behaviour
Watching a strategy lose four times in a row, even with simulated money, tells you whether you will let it run when the money is real. If you are tempted to switch it off, find out now.
How long should you paper trade an algo strategy?
The honest answer is "until you have enough trades", not "two to four weeks". The number of trades matters because a small sample tells you very little about the true win rate.
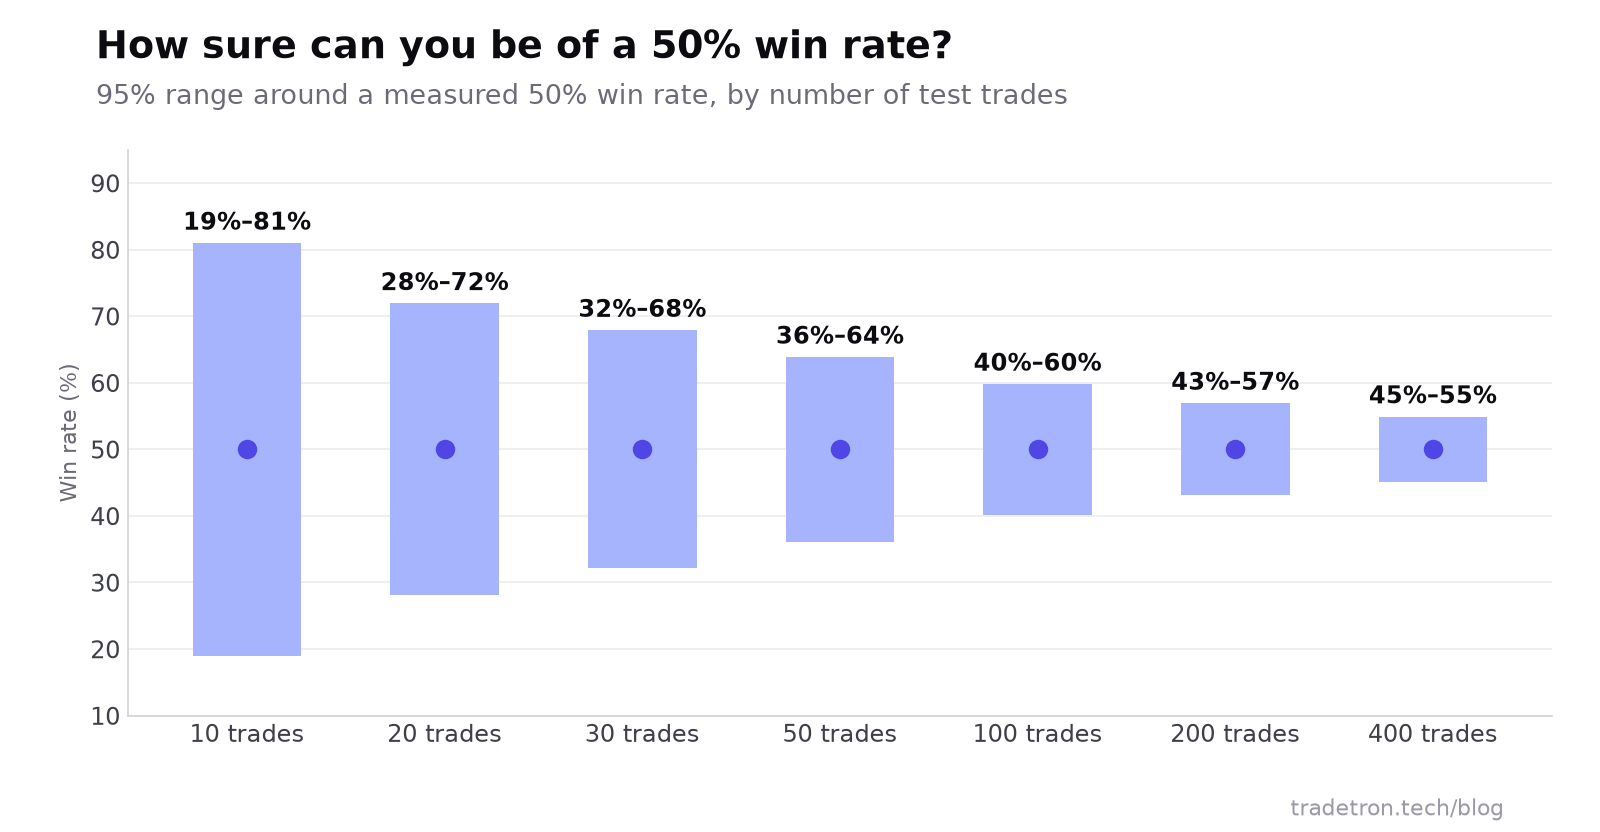 The fewer the trades, the less a measured win rate means
After 20 trades, a strategy showing a 50% win rate could plausibly have a true win rate anywhere from about 28% to 72%. That is the whole range from a losing system to a very good one. After 100 trades the range is 40% to 60%.
So:
- An intraday strategy that trades once a day gives you about 20 trades in four weeks: enough to check the build, not enough to judge the edge. Lean on the backtest for that.
- A positional strategy may trade a few times a month. Use the Live Offline run to check behaviour, not results.
- Judge results on the backtest and the live run together, and check that they agree.
A hypothetical example: what a test run can show
Say you have built a moving-average crossover on NIFTY futures, and the backtest looks good. You deploy it Live Offline for a month and read the log. Here is the kind of thing you might find:
Each of those would have cost real money to discover live. In Live Offline they cost nothing but time.
Your Live Offline checklist
- Deploy with realistic capital and size. The same lots you plan to trade live.
- Read the trade log daily for the first week. Every entry and exit should match a rule you can point to.
- Compare with a backtest of the same days. Same trades? Same prices, roughly? Find the reason for every difference.
- Track P&L after costs. Deduct charges and a slippage allowance per order.
- Change one thing at a time. If you fix a bug, note the date, re-backtest, and restart the comparison.
- Write down your go-live criteria before you start. For example: no unexplained trades for two weeks, and results within the range the backtest suggests.
What Live Offline can't test
A simulation never reaches the exchange, so some problems only appear with real orders:
- Slippage and partial fills, especially on market orders, far strikes and fast moves.
- Broker-side rejections, such as insufficient margin or an instrument your account isn't enabled for.
- Margin changes on volatile days, which affect how many lots you can actually hold.
- Connection issues between your broker and the platform.
That is why the next step is a small live run, not full size.
Going live without changing anything
When your criteria are met, go live with the same rules: change only the execution type and, if anything, reduce the size. Decide in advance the loss at which you will pause and review. Before switching, check what SEBI's algo-ID mandate means for your setup, and read seven ways to reduce drawdown.
For a full comparison of testing platforms and how to choose one, read the best paper trading platform in India.
Frequently asked questions
Is paper trading the same as backtesting?
No. Backtesting runs your rules on historical data. Paper trading runs them on today's live prices without real money. On Tradetron this is Live Offline: the strategy runs and records every trade, but nothing is sent to the exchange.
How long should I paper trade an algo strategy before going live?
Until you have enough trades to trust what you see and the trade log has no unexplained entries or exits. For a daily intraday strategy, a few weeks is enough to check the build; judging the edge needs the backtest and a larger sample.
Can paper trading show slippage?
Not reliably. Simulated fills usually happen at the trigger or last traded price. Add a slippage allowance per order when you judge the results, and confirm with a small live run.
Can I fully automate paper trades?
Yes. On Tradetron a strategy deployed Live Offline runs its rules on its own, exactly as it would in Live Auto, except that no order is sent to the exchange.
Why do my paper trading results differ from my backtest?
Common reasons are bar-based backtest data missing moves inside a candle, conditions evaluated at different moments, gaps at the open, and strike or expiry selection on live data. Compare trade by trade to find the cause.