₹50 Straddle Strategy: Creation and Optimisation by Backtesting
The ₹50 straddle strategy trades the at-the-money call and put once their combined premium drops below ₹50, which usually happens close to expiry. It started as a long straddle betting on a big expiry-day move, failed its backtest, and was flipped into a short straddle with a trailing stop and entry filters. This post walks through each version and what changed.
Where the idea came from
Every few weeks social media lights up with a screenshot of a cheap expiry-day option that multiplied many times in a single afternoon. The obvious question: what if you bought both the call and the put whenever they get cheap, so you catch the big move whichever way it goes? That is a long straddle, and it is easy to test.
The ₹50 straddle, buyer vs seller
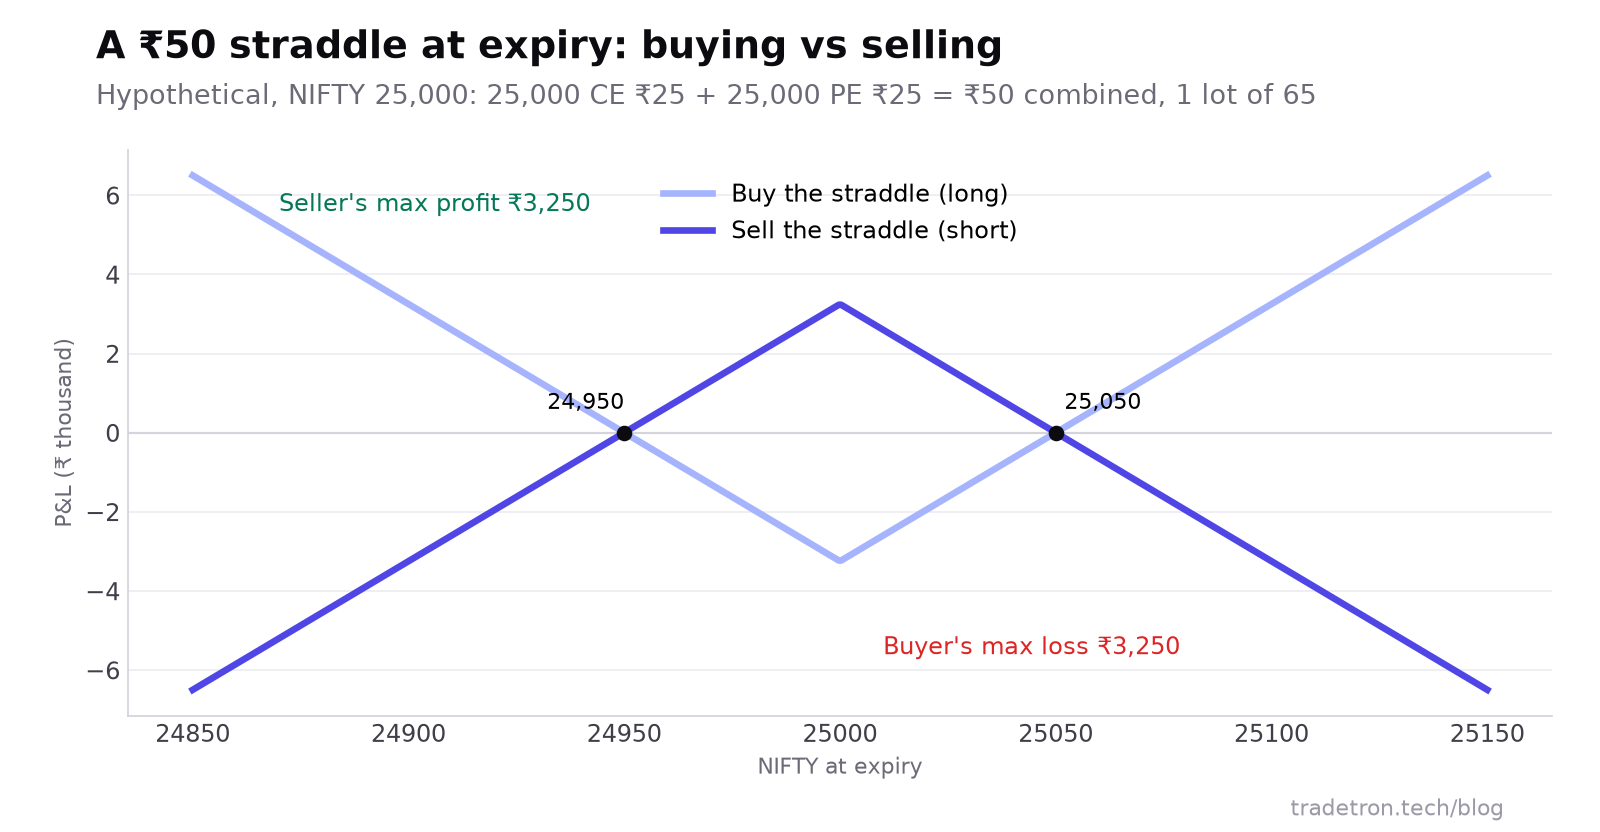 Hypothetical ₹50 straddle at the 25,000 strike, one lot of 65
A cheap straddle looks like a low-risk bet for the buyer: the loss is capped at ₹50. But the premium is cheap for a reason. With little time left, the market is pricing a small expected move, and most of the time it is right.
Version 1: buy the straddle
Backtested on 30 months of 1-minute data, the result was a flat, meandering equity curve that spent most of its time below zero. The occasional huge winner existed, but it was paid for by many small losses on days when the index barely moved.
Version 2: sell it, with a trailing stop
If buying the cheap straddle loses slowly most of the time, selling it should win slowly most of the time, with occasional sharp losses. So the strategy was reversed: sell the ATM call and put when their combined premium is under ₹50.
Selling without protection leaves the strategy exposed to the very move version 1 was hoping for. The fix was a trailing stop loss on the strategy's P&L:
- Sell the straddle when the combined premium falls below ₹50.
- Set a trailing stop on the total P&L, so the stop moves up as profit builds and a reversal closes the trade with part of the gain intact.
- Test several trailing values. Too tight and normal wiggles stop you out; too loose and a sudden move takes back everything.
- Pick a value that works across the whole period, not just the best single number, which is likely to be a fit to the past.
Selling plus a trailing stop turned the curve from flat to rising in the backtest, and the trailing-stop tests showed clear differences between values. That is the point of optimising a parameter: not to find a magic number, but to see how sensitive the result is to it.
Version 3: restrict the entries
The last round added two entry filters:
| Filter | Why |
|---|---|
| No new entries after 3:25 PM | Too little time left to manage the position or exit cleanly |
| Combined premium within a set range, not just below ₹50 | A straddle trading at ₹10 has little premium to earn and the same gap risk |
Comparing the restricted and unrestricted versions over the same 30 months, the restricted one showed slightly more profitable days. A small improvement, but one that comes from a reason you can explain, which makes it more likely to hold up than a filter found by trial and error.
Pros
- One clear trigger: combined premium below a threshold
- Short version earns from the fast time decay near expiry
- Trailing stop locks in part of the gains on calm days
- Simple to test and refine step by step
Cons
- Short straddle risk is unlimited on a big move
- Near-expiry options can jump faster than a stop can react
- Results depend on the trailing value chosen
- Index and expiry changes mean the original setup needs re-testing
Which index to use now
Since November 2024, the only weekly index expiries are NIFTY 50 on NSE (now on Tuesdays) and SENSEX on BSE (Thursdays). BANK NIFTY, FINNIFTY and MIDCPNIFTY are monthly only. A near-expiry strategy like this one now has a weekly opportunity on NIFTY and SENSEX, and a monthly one on the others. Re-run the backtest on the index you plan to trade.
Related builds: the ₹150 premium strangle with re-entry, the short straddle guide and how trailing stop losses work on Tradetron.
Frequently asked questions
What is a ₹50 straddle strategy?
It trades the ATM call and put together once their combined premium falls below ₹50, which usually happens close to expiry. The version that survived testing sells the straddle and manages it with a trailing stop loss.
Why did buying the cheap straddle not work?
Cheap straddles are cheap because the market expects a small move. On most days the index stays near the strike and both options decay to almost nothing. The rare big winners didn't make up for the frequent small losses in the backtest.
Is selling a straddle near expiry risky?
Yes. The premium collected is small, while a sharp move can cause losses many times larger. A trailing stop, a hard stop loss and small position size are essential.
How do I choose the trailing stop value?
Backtest several values and look for a range where results are reasonably stable, rather than the single best number. A value that only works at one exact setting is probably fitted to the past.
Which index should I run this on today?
NIFTY (weekly expiry on Tuesdays) or SENSEX (weekly on Thursdays) for a weekly version. BANK NIFTY, FINNIFTY and MIDCPNIFTY now have monthly expiries only.