Reducing Drawdown: 7 Risk-Management Techniques for Algo Traders
To reduce drawdown in algo trading, control how much you can lose before it happens: size each position so one loss is small, put a stop on every trade, cap the loss per day, hedge open-ended risk, spread capital across strategies that don't fail together, switch off in bad conditions, and test how deep the worst stretch could be.
How position size, a daily loss limit and stops keep drawdowns small, in 3 minutes. हिन्दी में देखें: Drawdown कैसे कम करें: risk के वो rules जो आपको trading में टिकाए रखते हैं, 3 मिनट में
What is drawdown, and why it matters more than returns
Drawdown measures how far your capital falls from its highest point before it recovers. If your account grows from ₹5,00,000 to ₹6,00,000 and then falls to ₹4,80,000, the drawdown is ₹1,20,000, or 20% of the ₹6,00,000 peak.
- ₹6,00,000 account peak
- ₹4,80,000 lowest point afterwards
- 20% drawdown
- 25% gain needed to get back to the peak
It matters more than returns for a simple reason: the deeper the hole, the harder the climb.
| Drawdown | Gain needed to recover |
|---|---|
| 10% | 11.1% |
| 20% | 25% |
| 30% | 42.9% |
| 40% | 66.7% |
| 50% | 100% |
Deep drawdowns also break people. Most traders abandon a strategy in the middle of its worst stretch, which is usually the worst time to stop. Keeping drawdown small is what lets you stick to a plan long enough for it to work.
1. Size every position by the risk, not the capital
Position sizing is the most powerful drawdown control you have. The idea: decide how much of your account you are willing to lose on one trade, then size the trade so that hitting the stop costs exactly that.
The same arithmetic shows why the percentage you choose matters so much. Losing streaks happen to every strategy, and here is what a streak does at different risk levels:
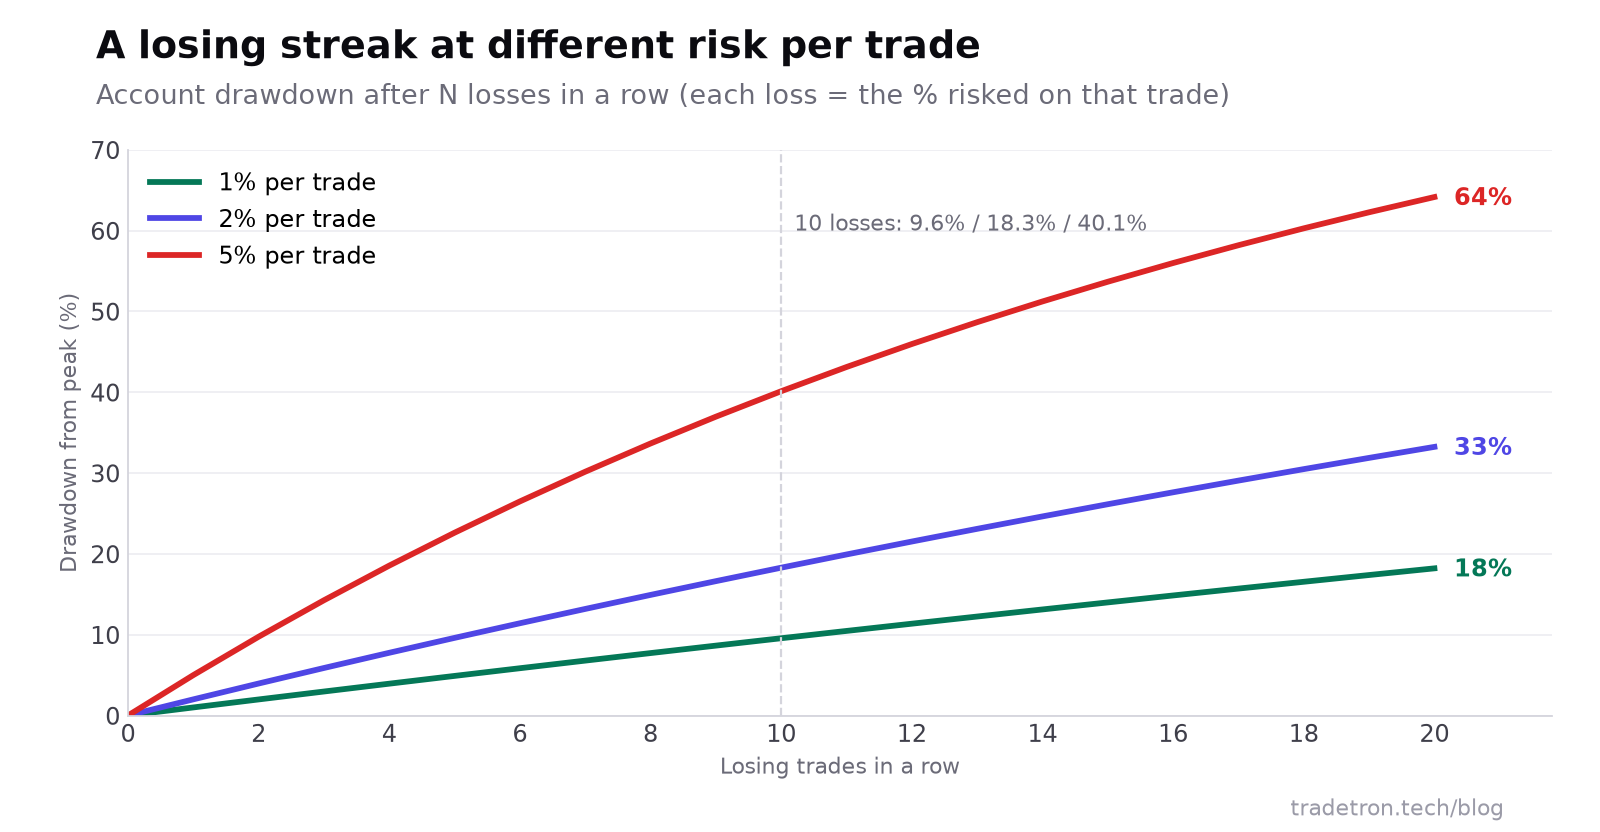 The same losing streak at three different position sizes
Two refinements:
- Volatility-adjusted size. When a stock or index is moving more than usual, a stop at the same distance gets hit more often. Using a stop based on ATR (average true range) and sizing from that distance keeps the rupee risk constant as volatility changes.
- Size for options by premium at risk. For option buyers, the premium is the maximum loss; for option sellers, the stop on the premium is. With NIFTY at 65 per lot, a stop that is 40 points away on a sold option risks 40 × 65 = ₹2,600 per lot.
2. Put a stop loss on every trade
A stop loss turns an unknown loss into a known one. There are several ways to place it, and each suits different strategies:
| Stop type | How it works | Good for |
|---|---|---|
| Fixed percentage | Exit if price falls X% from entry (e.g. the 7% rule) | Swing trades in stocks |
| Technical | Exit below a level that proves the idea wrong, such as a swing low | Breakouts and trend trades |
| Volatility (ATR) | Exit at entry − 2 × ATR | Instruments whose volatility changes a lot |
| Time | Exit if the trade hasn't worked by a set time | Intraday and expiry-day strategies |
| Trailing | Stop follows the price up and never moves down | Protecting open profit |
On Tradetron, each position (leg) can carry its own SL trigger condition, and a strategy can have a trailing stop loss on its total P&L.
3. Cap the loss per day
A per-trade stop doesn't stop a strategy from taking five bad trades in a day. A daily loss limit does: when the strategy's total loss for the day reaches a set amount, it closes everything and stops for the day.
On Tradetron you write this as a Universal Exit condition on the strategy's P&L (for example, PNL ≤ −7,500). A universal exit closes every open position of the strategy at once. You can add a maximum number of trades per day the same way, so a choppy day can't generate twenty losing entries.
4. Hedge risks that have no ceiling
Some positions can lose far more than you planned in a single gap move. A short straddle sold on NIFTY has no limit on how much it can lose if the index gaps 3% overnight. Buying a far out-of-the-money option on each side turns it into an iron fly or iron condor with a known maximum loss.
| Position | Maximum loss | Hedge |
|---|---|---|
| Short straddle or strangle | No limit | Buy OTM wings (iron fly or condor) |
| Short futures overnight | No limit | Buy a call, or reduce size before the close |
| Option buying | Premium paid | Already capped |
The hedge costs some premium, which lowers profit on good days. In exchange, a single bad day can't take a large bite out of the account. Read more in what hedging is and how to automate it and the iron condor guide.
5. Spread capital across strategies that fail at different times
Three NIFTY option-selling strategies are really one bet. When the market makes a big move, all three lose on the same day. Diversification only reduces drawdown if the strategies lose at different times.
- Mix styles: an option-selling strategy (does well in quiet markets) with a trend-following one (does well in big moves).
- Mix holding periods: intraday with positional.
- Mix instruments: index options with a basket of stocks.
- Check the overlap: put the daily P&L of each strategy side by side for the same period. If their worst days fall on the same dates, they aren't diversifying each other.
6. Switch off when conditions don't suit the strategy
Most strategies have conditions they hate. Option sellers suffer when volatility jumps; breakout strategies bleed in sideways markets. A regime filter is a rule that keeps the strategy out when its conditions aren't there.
Examples of filters you can write as entry conditions:
- Trade only when the 20-day ATR is below its 100-day average (a quiet-market filter for option selling).
- Trade a trend strategy only when price is above its 200-day moving average.
- Skip event days you've identified in advance, such as budget or policy announcement days.
Another simple filter is a pause after a bad stretch: stop the strategy after a set loss for the week and review it before restarting. It feels expensive when the market turns right after, but it is what stops a broken strategy from running into a much larger drawdown.
7. Test for the worst case, not the average
A backtest's total P&L tells you little about drawdown. Look at these instead:
- Maximum drawdown in the report, and how long it took to recover.
- The worst month and the worst day, and whether you could have sat through them.
- Different periods. Does the strategy survive both calm and volatile years?
- Nearby settings. If a stop of 25% works and 20% or 30% don't, the result is fragile.
- A safety margin. History never shows the worst drawdown the future holds. Plan for a deeper one than the backtest's, as a rough rule 1.5 to 2 times deeper, and size so you could survive it.
Tradetron's backtest form can run a sweep over several values of a setting and hold back part of the period to check the winner on data it hasn't seen. The backtesting guide explains the settings.
Pros
- Small, controlled drawdowns let you keep trading through bad stretches
- Rules like stops and daily limits are easy to automate and follow every time
- Smaller positions make it easier to stick to the plan
Cons
- Tighter risk usually means smaller profits on good days
- Hedges cost premium, and filters skip some winning trades
- No rule removes drawdown entirely; it only keeps it within a range you planned for
For the broader picture, read risk management in algo trading.
Frequently asked questions
What is drawdown in trading?
Drawdown is the decline from an account's or strategy's highest value to its lowest point before it makes a new high. It is usually shown as a percentage of the peak. Maximum drawdown is the largest such decline over the period you are looking at.
What is an acceptable drawdown for algo trading?
It depends on the strategy and on you. A useful test: could you keep the strategy running after losing that much? Many traders aim to keep maximum drawdown in the range they could sit through without changing the plan, and size positions so the backtest's drawdown, plus a safety margin, stays inside it.
How do I reduce drawdown in my trading strategy?
Reduce position size, put a stop on every trade, add a daily loss limit, hedge positions with unlimited risk, combine strategies that lose at different times, and avoid trading in conditions the strategy handles badly.
How much does it take to recover from a drawdown?
More than the loss. A 10% drawdown needs an 11.1% gain, a 20% drawdown needs 25%, and a 50% drawdown needs 100% to get back to the peak.
What is the difference between a loss and a drawdown?
A loss is the result of one trade. A drawdown is the cumulative fall across many trades, from a peak to a low. Several small losses in a row can add up to a large drawdown.
Should I stop a strategy during a drawdown?
Compare the drawdown with what the backtest showed. If it is within the range you planned for, stopping usually locks in the loss. If it is clearly deeper than anything in testing, or the market has changed in a way that breaks the strategy's logic, pausing to review is sensible.