What Is FII and DII? Their Role in the Stock Market
FII stands for Foreign Institutional Investor: a fund or institution based outside India that invests in Indian markets (officially called an FPI, Foreign Portfolio Investor, today). DII stands for Domestic Institutional Investor: Indian mutual funds, insurance companies, banks and pension funds. Both trade in very large sizes, so their daily net buying or selling is watched as a gauge of where big money is moving.
What is an FII (FPI)?
FIIs are institutions registered outside India that buy Indian shares, bonds and derivatives: pension funds, mutual funds, sovereign wealth funds, insurance companies, hedge funds and university endowments, among others.
Since SEBI's FPI Regulations of 2014, these investors are registered as Foreign Portfolio Investors (FPIs). The older "FII" label stuck in everyday use and in daily market reports, so you'll see both terms.
What drives their decisions:
- Global interest rates. When US yields rise, money tends to flow back to the US and out of emerging markets.
- The rupee. A falling rupee cuts a foreign investor's return in dollars.
- Relative valuations. India competes with other emerging markets for the same pool of money.
- Global risk appetite. In a global sell-off, foreign funds often reduce emerging-market holdings first.
What is a DII?
DIIs are Indian institutions that invest in the Indian market:
- Mutual funds, which invest the money that comes in through lump sums and monthly SIPs.
- Insurance companies, including LIC, the largest single domestic investor.
- Banks and financial institutions.
- Pension and provident funds, such as the NPS and EPFO.
What drives their decisions: mostly domestic. Mutual funds must invest the money investors give them according to each scheme's mandate, so steady SIP inflows mean steady buying. That is why DIIs often buy into falls that foreign investors are selling.
FII vs DII: key differences
| FII / FPI | DII | |
|---|---|---|
| Based in | Outside India | India |
| Examples | Foreign pension funds, sovereign funds, global mutual funds | Indian mutual funds, LIC and other insurers, banks, pension funds |
| Regulated as | Foreign Portfolio Investors under SEBI | Under SEBI, IRDAI, RBI or PFRDA depending on the type |
| Main drivers | Global rates, dollar and rupee, global risk mood | Domestic savings and SIP flows, scheme mandates |
| Typical behaviour | Can move in and out quickly and in size | Steadier, often buying when FIIs sell |
| Currency risk | Yes, returns are judged in dollars | No |
Why FII and DII flows move the market
Prices move when one side is more eager than the other. FIIs and DIIs trade in thousands of crores a day, so a sustained one-way flow from either can push the index for weeks.
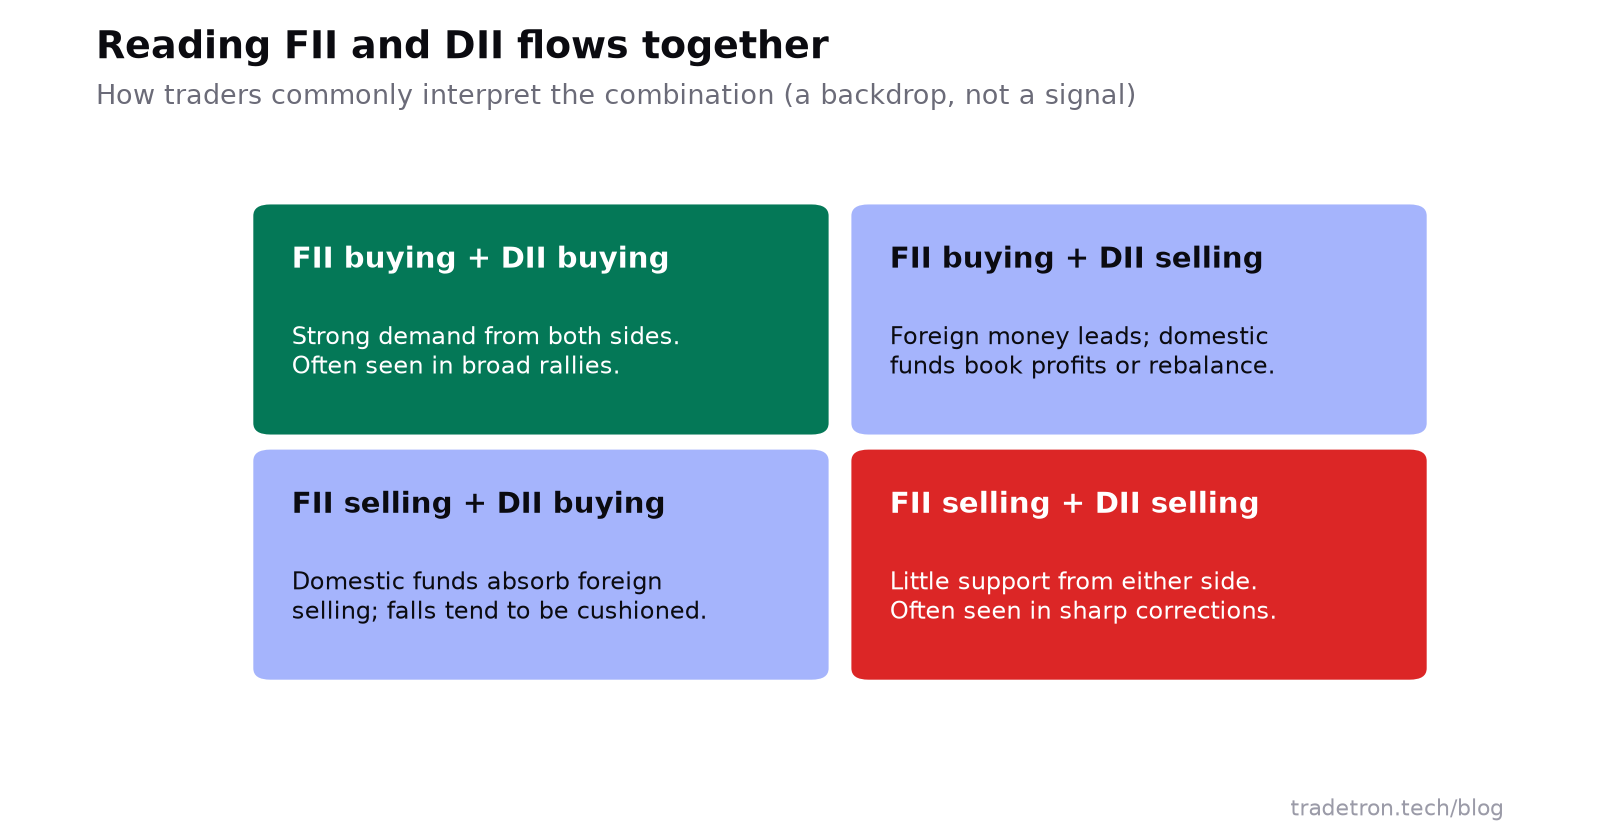 How the four combinations of flows are commonly read
A few patterns traders watch:
- Heavy FII selling with heavy DII buying has been common in recent years. The index may still fall, but domestic buying tends to slow the decline.
- Both selling removes the usual cushion. These periods tend to see the sharpest falls.
- Sector concentration. FIIs hold large stakes in big private banks, IT and other large caps, so their selling shows up most in those stocks and in the NIFTY itself.
Where to find FII and DII data
- NSE: publishes provisional FII/FPI and DII buy, sell and net figures for the cash market every trading day after the close.
- NSDL's FPI monitor: official FPI investment data, by equity and debt, published with a short lag.
- NSE participant-wise derivatives data: daily open interest in index futures and options split by FII, DII, proprietary traders and clients. Many traders find the FII position in index futures more telling than the cash figure.
How traders can use FII and DII data
- As market context. Weeks of FII selling with a falling rupee describe a risk-off backdrop. You might trade smaller or tighten stops.
- To understand a move. If the index fell sharply, the flow data shows who was selling.
- With derivatives positioning. FII net long or short positions in index futures show how foreign funds are positioned, not just what they bought today.
- Not as a standalone signal. The data is provisional, arrives after the close and is easy to over-read. A rule like "buy when FIIs are net buyers" is too blunt to trade on.
The signals you can act on are in price itself, which already reflects everyone's buying and selling, institutions included.
Turning a market view into rules
Related reading: NSE vs BSE, what an ETF is and how hedging works.
Frequently asked questions
What is the full form of FII and DII?
FII is Foreign Institutional Investor and DII is Domestic Institutional Investor. Foreign institutions are now officially registered as Foreign Portfolio Investors (FPIs), but "FII" is still widely used.
What is the difference between FII and DII?
FIIs are institutions based outside India investing in Indian markets; DIIs are Indian institutions such as mutual funds, insurers, banks and pension funds. FII flows depend more on global factors, while DII flows depend largely on domestic savings.
Is FII buying good for the stock market?
Sustained FII buying adds demand and usually supports prices, especially in large caps. But a single day's figure says little, and heavy buying can reverse quickly if global conditions change.
Why do DIIs buy when FIIs sell?
Mutual funds receive steady SIP and other inflows that they must invest according to each scheme's mandate, and insurers and pension funds invest for the long term. Falls driven by foreign selling often give them more attractive prices.
Where can I check daily FII and DII data?
NSE publishes provisional cash-market FII and DII figures after each trading day. NSDL publishes official FPI data, and NSE's participant-wise open interest shows how FIIs are positioned in index derivatives.
Is FII the same as FDI?
No. FIIs (FPIs) buy listed shares and bonds as portfolio investments, each holding under 10% of a company. FDI is a long-term strategic investment, usually 10% or more, often with management influence.