Option Selling Strategy: A Beginner's Guide for Indian Traders
An option selling strategy means writing (selling) options to collect the premium up front. You profit if the option loses value through time decay, a fall in implied volatility, or the market staying away from your strike, and you buy it back cheaper or let it expire worthless. The catch: your profit is capped at the premium, while a naked short option can lose many times that.
What is option selling?
When you buy an option, you pay a premium for a right. When you sell (write) one, you receive that premium and take on the obligation that comes with it: to sell the underlying at the strike (for a call) or buy it at the strike (for a put) if the option ends in the money. On NSE, index options are cash-settled, so in practice this means paying the difference in cash. Stock options are physically settled, so an in-the-money stock option can lead to delivery of shares.
| Option buyer | Option seller | |
|---|---|---|
| Premium | Pays it | Receives it |
| Maximum profit | Large (unlimited for calls) | The premium received |
| Maximum loss | The premium paid | Can be many times the premium (unlimited for naked calls) |
| Wins when | The market moves far enough, fast enough | The market stays away from the strike |
| Time decay | Works against you | Works for you |
| Margin | Only the premium | Margin required, often substantial |
You may have heard that most options expire worthless and that selling is therefore "easy money". Even when a sold option does expire worthless, the seller's results depend on the rare trades that don't, which is why risk management, not win rate, is the subject of most of this guide.
How option sellers make money
- Theta time value decays every day, fastest near expiry
- Vega premiums shrink when implied volatility falls
- Distance out-of-the-money options expire worthless if the market doesn't reach them
- Time decay. All else equal, an option is worth a little less each day. The decay speeds up in the last week, which is why many sellers trade close to expiry.
- Falling volatility. Before events, implied volatility rises and premiums swell. After the event, IV often drops sharply (an "IV crush"), shrinking premiums even if the market moved.
- Expiring out of the money. If the underlying never reaches the strike, the option expires worthless and the seller keeps the whole premium.
A NIFTY option selling example
NIFTY is at 25,000. You think it will stay below 25,300 until expiry and sell one lot of the 25,300 call at ₹120 (example premium).
| Detail | Value |
|---|---|
| Strike sold | 25,300 CE |
| Premium received | ₹120 |
| Lot size | 65 |
| Premium collected | ₹120 × 65 = ₹7,800 |
| Breakeven at expiry | 25,300 + 120 = 25,420 |
- NIFTY expires at or below 25,300: the call expires worthless. You keep ₹7,800.
- NIFTY expires at 25,500: the call is worth ₹200. Your loss is (200 − 120) × 65 = ₹5,200.
- NIFTY expires at 26,000: the call is worth ₹700. Your loss is (700 − 120) × 65 = ₹37,700, almost five times the premium you collected.
Now the same idea as a bear call spread: sell the 25,300 call at ₹120 and buy the 25,500 call at ₹60. Your credit falls to ₹60 (₹3,900 per lot), but the worst case is capped at (200 − 60) × 65 = ₹9,100, however far NIFTY rises.
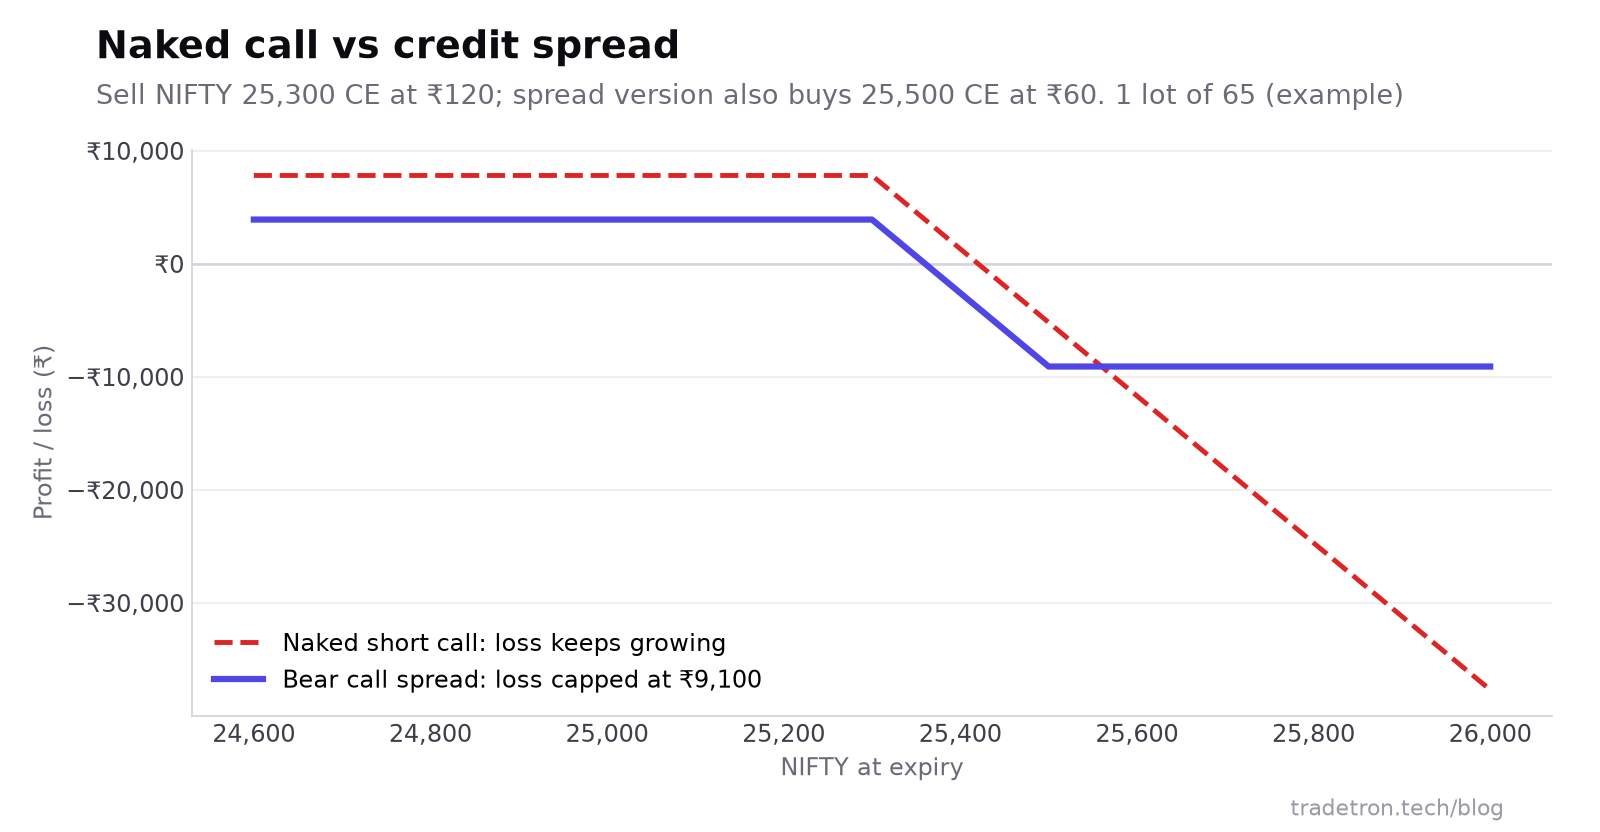 Buying a further-out call gives up half the premium and caps the loss
The risks every option seller must understand
- Unlimited or very large loss. A naked call has no upper limit on loss; a naked put can lose almost the full strike value.
- Gap risk. Overnight news can open the market far beyond your stop. Stop orders then fill at the next available price, not your level.
- Gamma risk near expiry. A cheap option two days before expiry can multiply in value if the market moves towards its strike. An option at ₹10 can be worth ₹100 or more within hours on expiry day.
- Volatility spikes. When uncertainty rises (RBI policy, the Union Budget, election results, global shocks), IV jumps and short options lose money even before the price moves.
- Margin calls. Losses and rising margin requirements can force you to close positions at the worst time.
Five common option selling strategies
| Strategy | Structure | Risk | Suits |
|---|---|---|---|
| Credit spread | Sell one option, buy a further OTM option on the same side | Defined | Beginners; a directional view |
| Iron condor | A call credit spread + a put credit spread | Defined | Range-bound markets |
| Short strangle | Sell OTM call + OTM put | Unlimited | Experienced sellers with strict stops |
| Covered call | Sell a call against shares you own | Same as owning the shares, minus the premium | Income on existing holdings |
| Cash-secured put | Sell a put with cash to buy the stock if assigned | Large, but planned | Investors willing to buy a stock lower |
Credit spreads
A bull put spread (sell a put, buy a lower put) profits if the market stays above the sold strike. A bear call spread (sell a call, buy a higher call) profits if it stays below. Maximum loss is the strike spacing minus the credit. This is the best place for beginners to start.
Iron condor
Two credit spreads at once, one above and one below the market. You collect premium from both sides with a capped loss. See the full iron condor guide with a NIFTY payoff.
Short strangle and short straddle
Selling an OTM call and put (strangle) or the ATM call and put (straddle) collects the most premium, with unlimited risk. They are widely traded, but only with per-leg stops and small size. See the strangle guide and the short straddle guide.
Covered call and cash-secured put
Both start from the stock rather than the option. A covered call adds premium to shares you already hold, but caps your upside. A cash-secured put pays you while you wait to buy a stock at a lower price. Remember that stock options in India are physically settled.
Weekly vs monthly option selling
NIFTY is the only NSE index with weekly options, expiring on Tuesday; SENSEX weeklies expire on Thursday on BSE. BANK NIFTY, FINNIFTY and MIDCPNIFTY have monthly expiries only.
| Weekly (NIFTY) | Monthly | |
|---|---|---|
| Time decay | Fast | Slower |
| Gamma risk near expiry | High | Lower |
| Time to adjust | Little | More |
| Premium per trade | Smaller | Larger |
| Typical use | Short holding periods, intraday | Positional trades with adjustments |
Risk rules for option sellers
- Know the worst case before entry. For a spread, it's the strike spacing minus the credit. For naked positions, pick a stop and estimate a gap beyond it.
- Size from capital, not from margin. If your capital is ₹2,00,000 and you risk 2% per trade, your maximum loss per trade is ₹4,000. The margin your broker allows is a different number. Check the live margin on your broker's calculator before sizing.
- Put a stop on every position, and honour it. For example: sold at ₹100, exit at ₹150. Decide it before entry so it isn't negotiated mid-trade.
- Reduce or hedge before events. Many sellers close or hedge positions before the Budget, RBI policy, results and election outcomes.
- Cap the day. A daily loss limit stops one bad session from becoming a bad month.
- Test first. Backtest across calm and volatile periods, then run the rules in a test mode before using real capital.
Why option sellers automate
Option selling is mostly about doing small, dull things on time: placing the hedge with the main leg, exiting a leg when it hits its stop, squaring off before the close, stopping for the day at the loss limit. Those are exactly the actions people delay when a position is moving against them. Rules don't.
For the bigger picture on protecting capital, read seven ways to reduce drawdown and our guide to NIFTY hedging strategies.
Frequently asked questions
Is option selling safer than option buying?
Not in general. Buying has a small, capped loss but loses more often. Selling wins more often but can lose much more on a single trade, unlimited for a naked call. Hedged selling (spreads) sits in between, with defined risk.
Why does time decay help option sellers?
Every option's time value falls as expiry approaches, faster in the last few days. The seller received that time value up front, so as it decays, the option becomes cheaper to buy back, which is the seller's profit.
Can beginners start with option selling?
Yes, with defined-risk strategies such as credit spreads or iron condors, small size, a stop on every position, and time spent testing the rules first. Naked selling is not a good place to start.
How much capital do I need to sell options in India?
It depends on the instrument, the strategy and current margin rules. Naked short options need substantial margin; hedged positions need less. The more useful number is how much you can afford to lose on one trade, which should set your size. Check your broker's margin calculator for current figures.
What is the difference between a credit spread and naked option selling?
A credit spread sells one option and buys a further out-of-the-money option on the same side, capping the maximum loss at the strike spacing minus the credit. A naked sale has no such cap.
Can option selling strategies be automated?
Yes. On Tradetron you can automate entries, strike selection, per-leg stop-losses, hedges, daily loss limits and exits without code, and test them with a backtest and Live Offline before going live.