Long Straddle Strategy: A Beginner's Guide to Trading Big Moves
A long straddle means buying one at-the-money call and one at-the-money put on the same underlying, with the same strike and expiry. It profits if the market moves far enough in either direction to cover the combined premium, and loses if the market stays flat, because time decay and falling volatility eat into both options. Your maximum loss is the premium paid.
Long straddle at a glance
| Market view | Big move expected, direction unknown |
| Structure | Buy ATM call + buy ATM put, same strike and expiry |
| Maximum loss | Total premium paid |
| Maximum profit | Open-ended above; large below |
| Breakevens | Strike ± total premium |
| Helped by | A large move, rising implied volatility |
| Hurt by | Time passing, falling implied volatility |
How a long straddle works: a NIFTY example
NIFTY is at 25,000 and the RBI policy announcement is tomorrow. You expect a sharp reaction but can't tell which way. You buy (example premiums):
If NIFTY rises sharply, the call gains far more than the put loses. If it falls sharply, the put does the work. If it stays near 25,000, both options lose value.
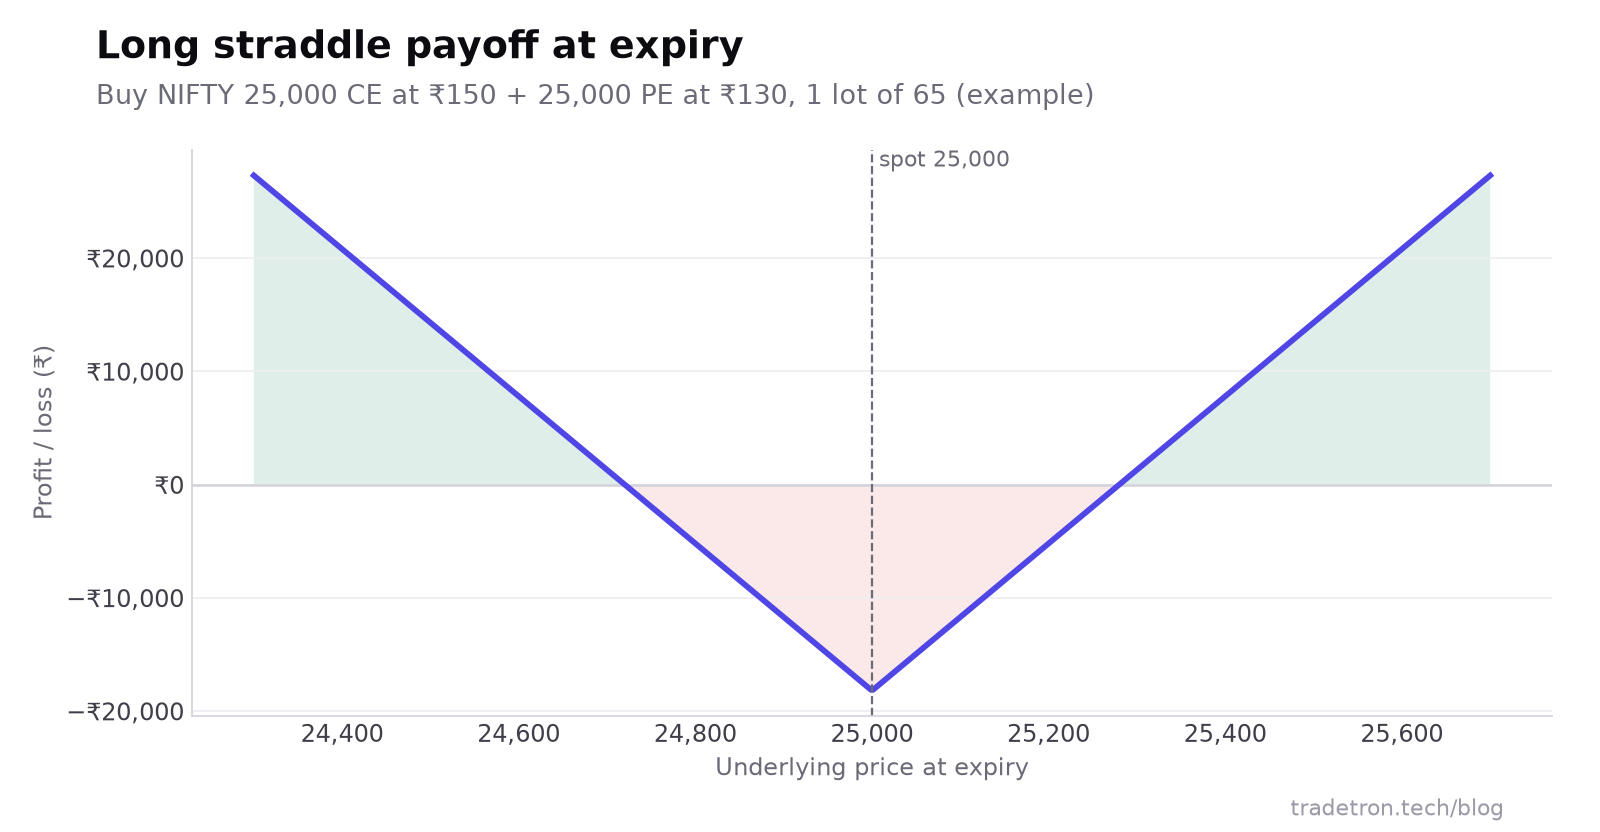 The long straddle's V: a capped loss in the middle, profit beyond either breakeven
| NIFTY at expiry | Call value | Put value | Profit / loss per lot |
|---|---|---|---|
| 24,500 | 0 | 500 | (500 − 280) × 65 = +₹14,300 |
| 24,720 | 0 | 280 | ₹0 (breakeven) |
| 25,000 | 0 | 0 | −₹18,200 |
| 25,280 | 280 | 0 | ₹0 (breakeven) |
| 25,500 | 500 | 0 | (500 − 280) × 65 = +₹14,300 |
The two forces working against straddle buyers
1. Theta: time decay
Both options lose time value every day. With no movement, a call bought at ₹150 and a put at ₹130 might be worth ₹140 and ₹120 the next day: a ₹20 per unit loss (₹1,300 per lot) without the market doing anything. Decay accelerates in the final days before expiry.
2. IV crush
Before a known event (RBI policy, the Union Budget, results, election outcomes), implied volatility rises because everyone expects a move. Premiums get expensive. Once the event passes, IV usually drops sharply, and both legs lose value at once, sometimes even after a decent move.
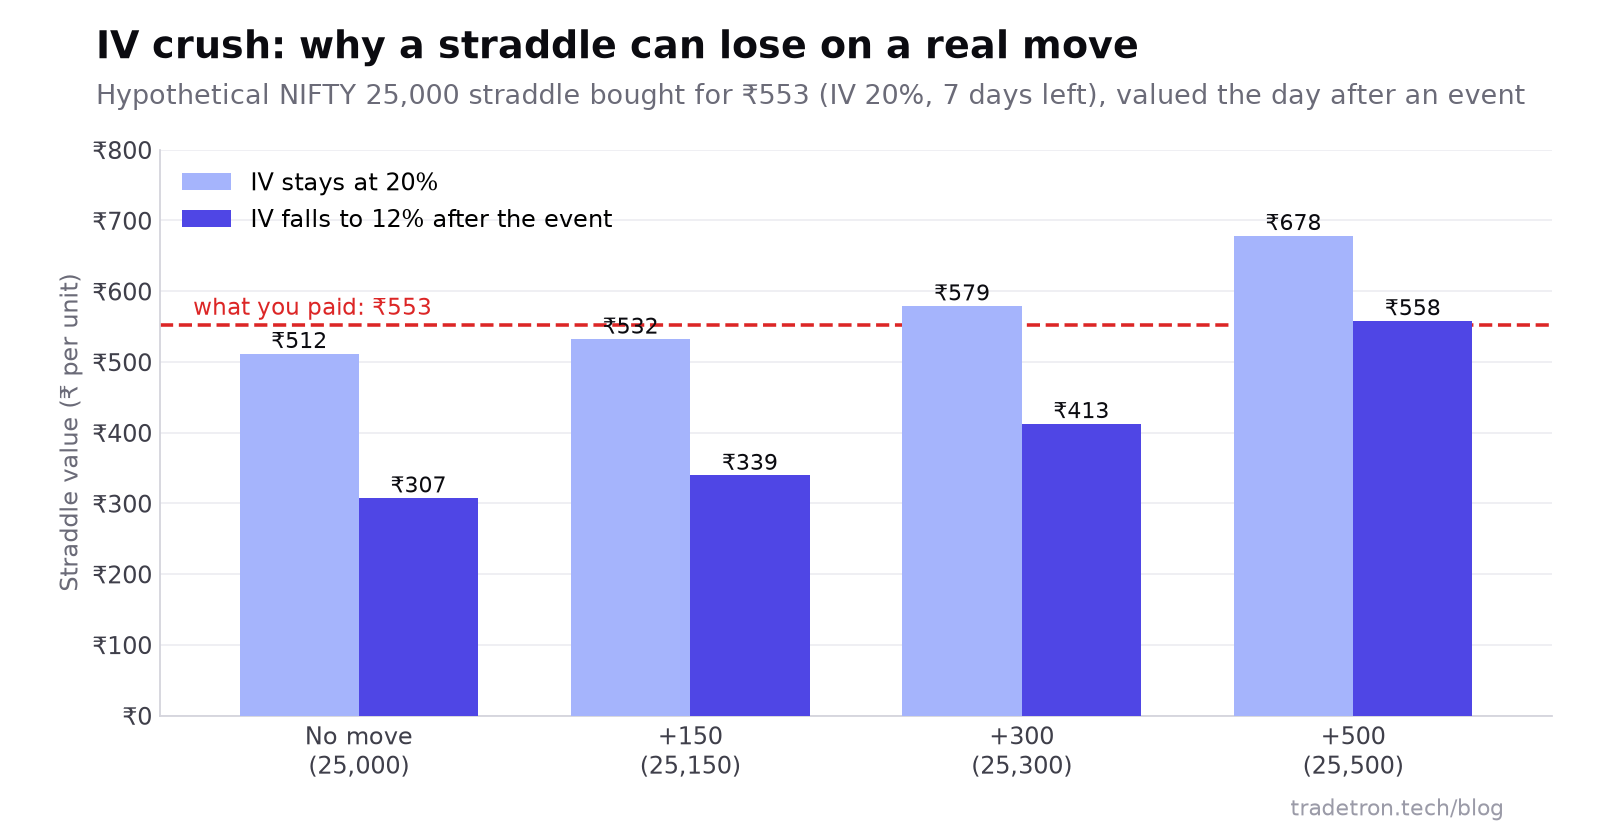 With IV collapsing after the event, even a 300-point move leaves this straddle at a loss (model prices)
Long straddle vs short straddle
| Long straddle | Short straddle | |
|---|---|---|
| Position | Buy call + buy put | Sell call + sell put |
| Profits when | Big move, either direction | Little or no movement |
| Volatility | Benefits from rising IV | Benefits from falling IV |
| Maximum loss | Premium paid | Unlimited |
| Maximum profit | Open-ended | Premium received |
The short version is a different strategy with very different risk: see the short straddle guide.
When traders use a long straddle
- Before major binary events where direction is genuinely uncertain: RBI policy, the Union Budget, US Fed decisions, election results, or results for a single stock.
- After a long, tight range, when volatility is low and options are cheap, in anticipation of a breakout.
- When defined risk matters. You know the maximum loss before you enter.
Not every event deserves a straddle. If IV is already elevated, the premium may already price in the move you expect.
If the move hasn't come
If the event has passed and NIFTY is still near your strike, don't hold and hope. Either close and accept the defined loss, or roll to a later expiry if your reason for expecting a move is still valid, paying extra premium for the extra time. Rolling only to avoid booking a loss is how small losses become big ones.
Straddle vs strangle
A long strangle buys out-of-the-money options instead (for example, the 25,300 call and 24,700 put). It costs less but needs a bigger move to profit. See the full comparison in straddle vs strangle and the strangle guide.
How much capital you need
One lot of an ATM NIFTY straddle costs the combined premium × 65. At ₹280 that's ₹18,200; at ₹230 it would be ₹14,950. Premiums are higher before events and with more time to expiry. If your capital can't cover a full lot within your risk limits, a cheaper far-OTM version usually isn't the answer: it has a much lower chance of paying off.
Risk management on a straddle
- Stop on the combined premium, not on each leg. One leg is supposed to lose.
- Time exit. If the event has passed and the move hasn't come by a set time, exit. A dead straddle only decays.
- Target on the combined premium. Take profits into a sharp move; IV can fall quickly afterwards.
- Avoid expiry day. Decay is at its fastest; even a real move may not outrun it.
Common mistakes beginners make
- Buying straddles on expiry day
- Ignoring how high IV already is before entry
- Holding without a predefined stop or time exit
- Trading every scheduled event instead of the genuinely uncertain ones
- Thinking only about direction, and forgetting time and volatility
A long straddle trade, start to finish
- Form the view. NIFTY at 25,000, RBI policy tomorrow, no clear consensus. Check that IV isn't already so high that the move is fully priced in.
- Write the entry rules. Buy the 25,000 CE and PE one or two sessions before the event, never on expiry day. Cost ₹280 (₹18,200 per lot). Breakevens 25,280 and 24,720.
- Write the exits. Stop at a combined premium of about ₹249 (2% of ₹1,00,000), a profit target on the combined premium, and a time exit after the event.
- Profit scenario. The decision surprises; NIFTY opens at 25,500. The call jumps, the put fades, the combined premium clears the target. Exit into strength.
- Loss scenario. The decision is as expected; NIFTY sits near 25,050 and IV collapses. The combined premium slides towards ₹249 and the stop or time exit closes the trade at a defined loss.
Either way, the decisions were made before the trade, not under pressure during it.
Frequently asked questions
What is a long straddle strategy?
A long straddle is buying an at-the-money call and an at-the-money put with the same strike and expiry. It profits from a large move in either direction and loses if the underlying stays near the strike.
Is a straddle bullish or bearish?
Neither. A long straddle is direction-neutral. It needs a move beyond either breakeven, up or down, and loses if the market stays in a range.
What is the maximum loss on a long straddle?
The total premium paid for both options. In the NIFTY example that is ₹280 per unit, or ₹18,200 per lot of 65, lost in full only if NIFTY expires exactly at the strike.
How is the straddle breakeven calculated?
Upper breakeven = strike + total premium. Lower breakeven = strike − total premium. With a 25,000 strike and ₹280 premium, they are 25,280 and 24,720.
Why do straddles lose money even when the market moves?
Because of time decay and IV crush. If implied volatility collapses after the event, both options lose value at once, and a move smaller than the one priced in isn't enough to make up for it.
When is the best time to buy a straddle?
When a large move is genuinely uncertain and implied volatility isn't already stretched: often a session or two before a major event, or after a long period of unusually low volatility. Avoid expiry day.
What is the difference between a straddle and a strangle?
A straddle uses the same at-the-money strike for both options; it costs more but breaks even sooner. A strangle uses out-of-the-money strikes; it costs less but needs a bigger move.